
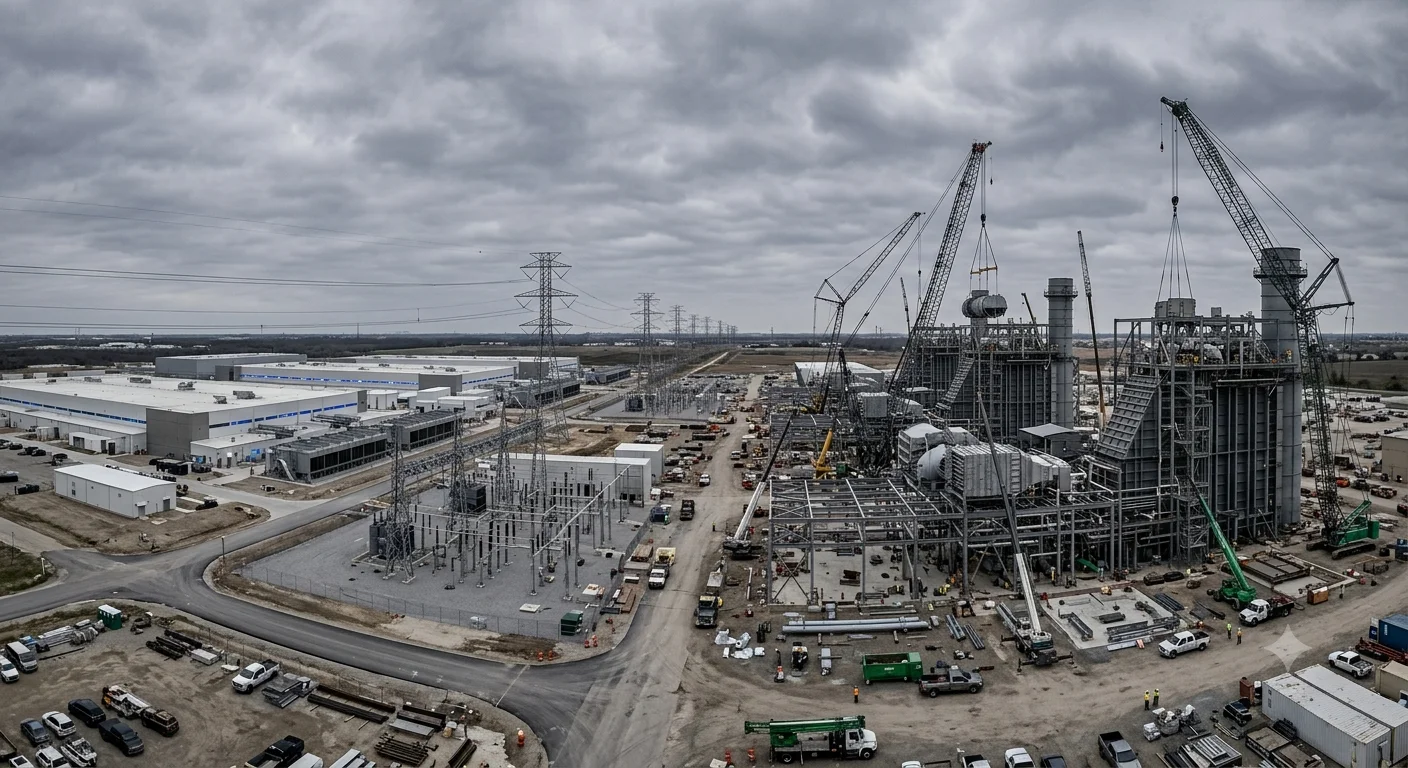
Artificial intelligence is rewriting the economics of energy infrastructure. Tech companies are building natural gas power plants at a pace the construction industry was not prepared to absorb. As a result, costs have responded exactly as constrained supply chains always do — they have climbed sharply. The cost to build a combined-cycle natural gas power plant has surged 66% over the last two years alone. Moreover, that figure does not capture the full picture. Equipment lead times, labor shortages, and a concentrated burst of simultaneous projects are compounding the pressure in ways that raw cost indices do not fully reflect.

The Rush to Gas and Why It Happened
For most of the last decade, tech companies treated energy as a procurement problem rather than a construction one. However, the AI buildout changed that calculation almost overnight. Data centers running GPU clusters require firm, dispatchable power — electricity that arrives on demand regardless of weather or time of day. Consequently, wind and solar alone cannot satisfy that requirement without substantial storage backup. Natural gas fills that gap cleanly, burning on demand and scaling output within minutes.
Therefore, hyperscalers and their infrastructure partners began signing agreements to build dedicated gas plants adjacent to data center campuses. Microsoft committed to gas-backed generation for several of its AI facility expansions. Meta followed a similar path, backing dedicated gas infrastructure to guarantee power delivery timelines. Meanwhile, Amazon, Google, and Oracle each pursued gas-inclusive power strategies for facilities that could not wait years for renewable interconnection. Instead of purchasing power from the grid, these companies began building the generation layer themselves.
What a 66% Cost Increase Actually Means
The numbers behind this surge require precise framing. A combined-cycle natural gas plant that cost approximately $900 per kilowatt to build two years ago now costs closer to $1,500 per kilowatt. For a 500-megawatt facility — a mid-sized plant by hyperscale standards — that difference translates to roughly $300 million in additional capital expenditure on a single project. Moreover, larger multi-gigawatt commitments amplify that figure proportionally. Consequently, the financial assumptions underpinning power procurement agreements signed in 2023 and 2024 no longer reflect current construction economics. As a result, several developers are renegotiating cost structures with utility partners and grid operators to recover expenses that were not anticipated at contract execution. However, renegotiation is not always straightforward, particularly where fixed-price agreements exist with public utilities subject to regulatory oversight. Therefore, some cost exposure is being absorbed directly by the technology companies themselves rather than passed through to the power purchase agreements.

The Supply Chain Behind the Price Spike
Understanding why costs jumped 66% requires looking beyond headline inflation. Several distinct supply chain pressures have converged simultaneously, each reinforcing the others. Gas turbines represent the most acute bottleneck. The two dominant global suppliers of large gas turbines — Siemens Energy and GE Vernova — are running order backlogs that stretch two to three years in many configurations. Therefore, a developer who decides today to build a natural gas plant cannot receive the core generation equipment until 2027 at the earliest. Moreover, transformer supply faces comparable pressure.
High-voltage transformers, essential for connecting generation to transmission infrastructure, now carry lead times of 80 to 120 weeks from order to delivery. Meanwhile, skilled labor for gas plant construction has not scaled proportionally with demand. Consequently, contractors are bidding aggressively for the same pool of qualified workers — pipefitters, boilermakers, instrumentation technicians — driving wage rates well above the levels reflected in pre-2024 project estimates. As a result, labor now accounts for a larger share of total project cost than at any point in the last fifteen years.
Tech Giants Feeling the Squeeze
Not every company has absorbed these pressures equally. However, the largest hyperscalers have moved to lock in turbine orders and construction commitments earlier in their planning cycles, recognizing that waiting compounds both cost and timeline risk. Microsoft has publicly acknowledged that its capital expenditure trajectory reflects the rising cost of power infrastructure, not solely server hardware and real estate. Meta has similarly indicated that infrastructure spending is increasing faster than previously modeled. For example, Meta’s data center-related capital expenditure guidance for 2026 was revised upward twice in the first two quarters of the year.
Consequently, investors tracking AI infrastructure spending now monitor power plant construction costs as a direct variable in hyperscaler profitability modeling — a shift from previous cycles where energy was treated as an operating rather than capital expense. Meanwhile, smaller cloud operators and colocation providers face a harder version of the same problem. They lack the scale to secure multi-year turbine manufacturing slots or negotiate preferential equipment delivery agreements. As a result, second-tier developers are increasingly dependent on third-party power purchase agreements rather than self-build options.
The Regulatory and Ratepayer Dimension
The cost surge does not exist in a policy vacuum. State utility regulators in Virginia, Missouri, Texas, and several other major data center markets are actively examining how large-load power commitments affect grid reliability and ratepayer costs. However, a structural change is underway. Several states have moved toward Capacity Commitment Frameworks — regulatory structures requiring large energy users to pay directly for the infrastructure their demand creates. Missouri adopted this model in 2026, with both Google and Amazon committing to cover 100% of grid connection costs for their Montgomery County campuses.
Consequently, the political and regulatory environment is tightening around the assumption that tech companies can access utility infrastructure at standard ratepayer rates. Therefore, the true cost of gas-backed power for data centers includes not only plant construction but also transmission infrastructure, grid connection fees, and increasingly, community mitigation contributions. Moreover, some state legislatures are considering requirements that large gas plants built for data center use meet specific carbon offset or clean fuel blending standards within defined timeframes. As a result, the regulatory cost stack sitting above the 66% construction cost increase is itself expanding in ways that will affect project financial modeling through the end of the decade.
Where This Leaves the Industry
The 66% construction cost surge does not stop the build — AI infrastructure investment has too much momentum behind it for rising gas plant costs to reverse the direction of capital flow. However, it does reshape the competitive landscape in ways that will play out over the next several years. Developers who moved earliest on turbine orders and site permits have locked in cost structures that later entrants cannot match. Consequently, first-mover advantage in power infrastructure has taken on a financial dimension that adds to the strategic one. Meanwhile, rising gas plant costs are accelerating genuine interest in alternatives. Nuclear options — particularly SMRs and advanced reactor designs — are attracting more serious evaluation from hyperscalers who are now comparing a 66%-inflated gas plant cost against the declining projected cost of modular nuclear.
For example, Microsoft, Google, and Amazon have each signed nuclear power agreements in the last 18 months, and the cost trajectory of gas construction is one factor making those commitments easier to justify internally. Moreover, behind-the-meter renewable-plus-storage configurations are becoming more cost-competitive as battery storage prices continue to fall. Therefore, the natural gas surge is not a permanent equilibrium — it is an inflection point, one that makes alternatives more attractive precisely as their own economics continue to improve. The companies that use this cost pressure as a forcing function to diversify their power strategies will be better positioned than those that simply absorb higher construction costs and proceed with gas as the default.











