Skip to content

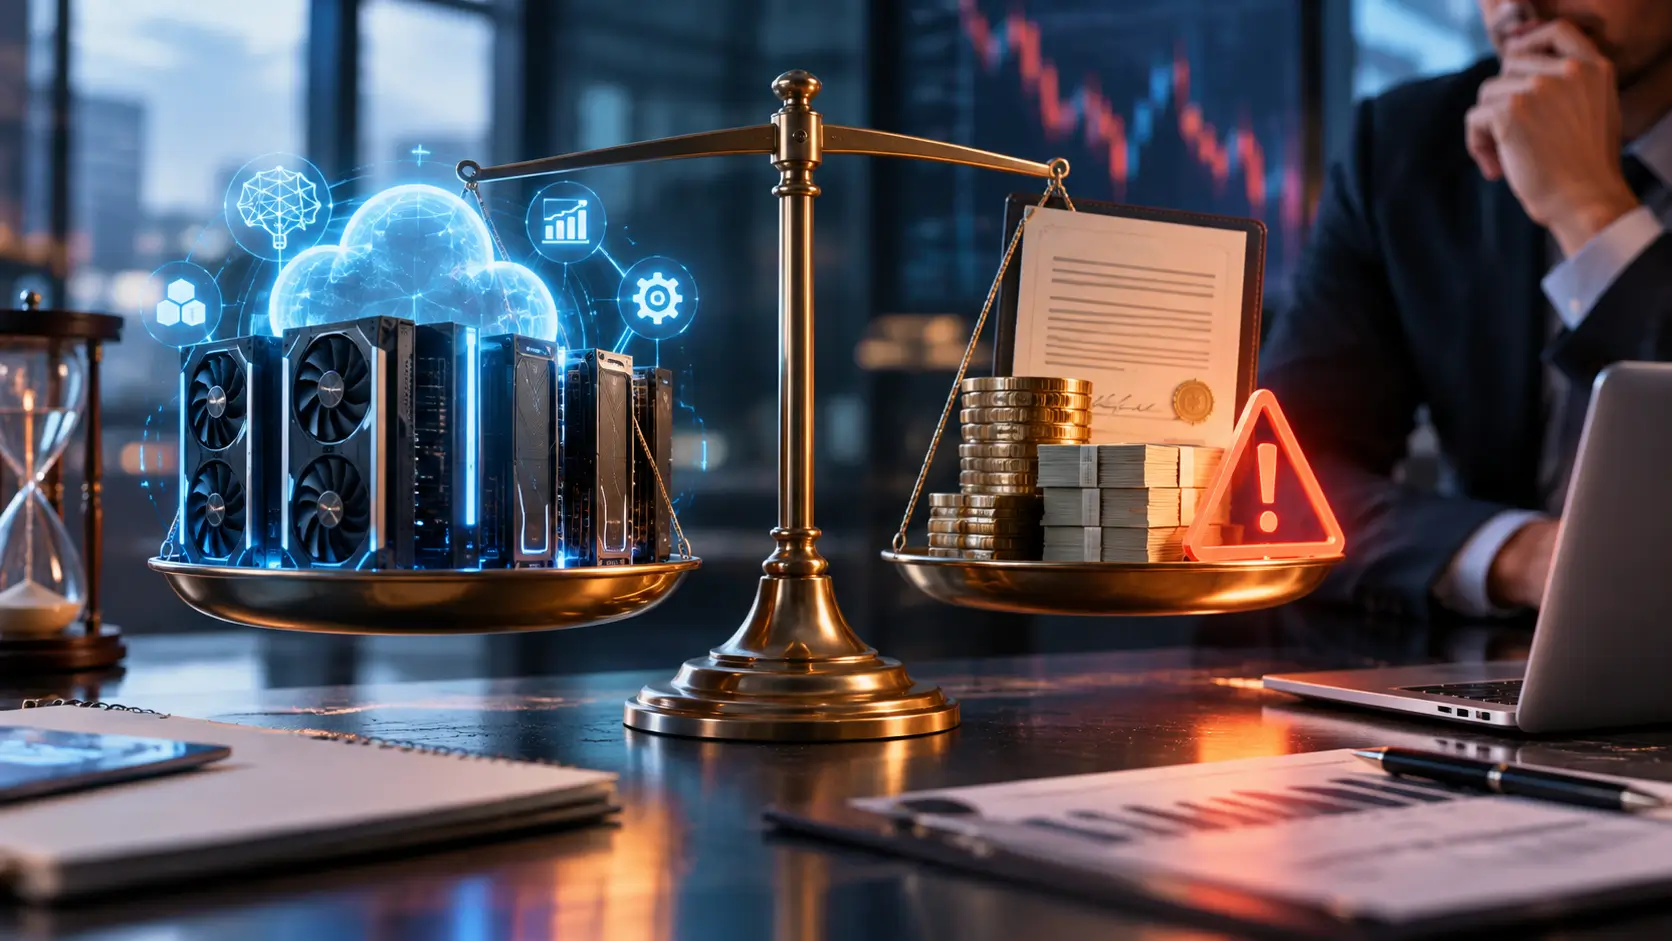
AI buyers often reserve compute because waiting for capacity can disrupt deployment plans. A reservation gives the buyer contractual access to specified GPU capacity for future workloads. The financial picture becomes more complicated when that commitment extends across several years. Workload requirements may change long before the contract ends. Yet payment obligations may continue according to terms negotiated when demand looked different. This gap can affect cash planning, operating flexibility, and future infrastructure decisions. It also matters because a commercial commitment does not always create an immediate accounting liability. Finance teams must therefore examine expected utilization, payment schedules, termination rights, and accounting treatment together.

Capacity Reservations Move Risk Before Compute Arrives
A reservation can give an AI buyer greater certainty about future infrastructure access. That certainty may come with a commitment to purchase a specified amount of capacity. If workload demand later falls below expectations, the contracted spending may remain unchanged. CoreWeave, for example, says customers generally access its platform through multi-year committed contracts. Under these contracts, customers purchase specified capacity on a take-or-pay basis. The company reported a weighted-average duration of about five years for committed contracts at the end of 2025. Those terms describe one provider and should not represent the entire neocloud market. Still, they show why buyers need to examine how long their spending obligations can continue. Financial pressure develops when the contracted spending schedule becomes harder to change than the workload forecast supporting it.
Take-or-Pay Changes the Economics of Underutilization
A usage-based service can allow spending to fall when customers consume less infrastructure. Take-or-pay arrangements can produce a different outcome. Customers may still owe contracted amounts when actual consumption falls below purchased capacity. Utilization then becomes a financial issue as well as an infrastructure metric. An AI team could receive the promised GPUs while leaving part of the capacity unused. In that situation, the commercial value generated from the contracted spending can decline. CoreWeave reported that committed contracts accounted for more than 98% of its 2025 revenue. The company also says these arrangements generally require customers to purchase specified capacity on a take-or-pay basis. Finance teams should separate contracted payments, expected consumption, and amounts recognized in financial statements when assessing such arrangements.
A Commercial Commitment Is Not Automatically a Balance-Sheet Liability
Long-term infrastructure commitments do not automatically create an immediately recognized liability. Accounting treatment depends on the substance and terms of each arrangement. Under U.S. accounting guidance, certain cloud computing arrangements without software licenses receive service-contract accounting treatment. Hosting costs generally reach the income statement as customers receive the service, subject to applicable guidance and contractual facts. FASB guidance separately addresses eligible implementation costs associated with these arrangements. Companies can capitalize qualifying implementation costs and recognize them over the relevant hosting arrangement. A large contractual commitment and a large recognized liability therefore do not necessarily represent the same amount. Other contractual elements may require separate analysis when customers receive rights over identifiable infrastructure. Finance leaders need to consider accounting recognition alongside the broader economic exposure created by future payments.

The Lease Question Can Change the Accounting Picture
Some capacity arrangements require closer review when customers receive rights involving identifiable infrastructure. IFRS 16 considers whether a contract gives the customer control over the use of an identified asset for a period in exchange for consideration. The analysis includes the customer’s ability to obtain substantially all economic benefits from that asset. It also examines whether the customer has the right to direct its use. An asset may receive explicit or implicit identification under the standard. Substantive supplier substitution rights can affect whether an identified asset exists for this purpose. U.S. GAAP under ASC 842 applies related concepts involving identified assets and customer control. Generic GPU capacity drawn from an interchangeable fleet should not automatically receive lease treatment. Dedicated infrastructure can require closer analysis, but dedication alone does not establish a lease because the relevant control requirements must also exist.
The Bigger Risk May Sit Outside the Reported Liability Number
Financial statements cannot answer every question about a multi-year compute reservation. A business may face substantial future cash commitments without showing the entire undiscounted amount as one conventional liability when it signs the agreement. Management still needs sufficient liquidity to meet payments as they become due. A reservation that appears affordable under rapid growth assumptions may look different if product adoption develops more slowly. Supporting an AI workload can also require networking, storage, software, personnel, and other infrastructure. The scale of those requirements depends on the architecture and purchasing model used by the buyer. Their accounting treatment may also differ from that of the compute reservation itself. Finance teams should examine the combined cash requirements instead of treating GPU spending as an isolated technology budget. Risk increases when difficult-to-reduce spending commitments depend on uncertain future economic output.
Utilization Becomes a Finance Metric
Infrastructure teams usually discuss GPU utilization in relation to scheduling, workload placement, and cluster efficiency. Committed capacity adds a financial dimension to the same metric. Sustained unused capacity can reduce the economic productivity of spending when a buyer pays for a fixed allocation. That does not mean every GPU must operate at maximum utilization. Buyers may intentionally maintain headroom for workload variation, testing, resilience, or planned growth. The financial question concerns whether that headroom provides enough value to justify its cost. Lower initial utilization may make commercial sense when workloads have credible expansion plans. Repeated demand shortfalls create a different situation when contractual payments continue unchanged. Finance and infrastructure teams should therefore connect measured workload demand with committed units, payment timing, and expected business output.
Prepayments Shift Risk Earlier in the Contract
Some capacity agreements require customers to provide cash before they receive the corresponding service. CoreWeave says its committed contracts typically include customer prepayments before customers gain access. At the end of 2025, weighted-average prepayments across its active contracts ranged from 15% to 25% of total contract value. These figures apply to CoreWeave and should not serve as an industry-wide benchmark. They nevertheless illustrate how a capacity agreement can move part of the cash requirement forward. A prepayment places some customer cash with the provider before the related service period. Its financial effect depends on the individual contract and applicable accounting treatment. Early cash deployment can also reduce funds available for other business priorities. Treasury teams should model that timing when evaluating a large reservation. Negotiators should examine prepayment percentages, refund provisions, service credits, milestones, and service commencement conditions before approving the agreement.
Delivery Timing Can Distort the Original Business Case
Capacity creates the intended commercial value when the buyer can use it at the required time. Late infrastructure availability can weaken a business case built around a particular product schedule. Early availability can create another problem if workloads are not ready when charges begin. Buyers should therefore define availability dates and acceptance conditions clearly in their contracts. Contractual remedies also matter when providers fail to meet agreed service requirements. Infrastructure expansion depends on the availability of numerous hardware and facility components. CoreWeave says it relies on a limited number of suppliers for significant infrastructure components. The company also warns that supply disruptions could delay capacity expansion or replacement of defective equipment. That disclosure does not mean a particular reservation will face delays, but it supports treating delivery timing as a contractual risk rather than an automatic assumption.
Contract Flexibility Determines How Quickly Exposure Can Shrink
Long-term reservations become harder to manage when buyers have few options for changing capacity after demand shifts. Termination provisions can determine whether customers can exit before the original contract ends. Step-down rights may provide another mechanism when the agreement expressly permits lower future capacity. Assignment, renewal, substitution, and service-credit provisions can also influence commercial flexibility. Their accounting effects depend on the specific contract and applicable standards. Operationally, these rights determine which actions remain available when actual requirements differ from the initial forecast. A contract may also allow capacity to move between compatible services or locations. Buyers should verify those rights instead of assuming that such flexibility exists. Lower unit pricing does not automatically produce lower total spending when the discount requires greater volume or a longer commitment.
Hardware Flexibility Matters During Multi-Year Commitments
Technical requirements can change while a multi-year agreement remains active. Buyers should therefore determine exactly which infrastructure the reservation covers. A contract tied to a specific accelerator configuration may provide different flexibility from one that permits agreed substitutions. Procurement teams should verify whether replacement hardware can satisfy the original commitment. They should also establish who decides when a substitution occurs. The accounting implications may require separate analysis when identified assets form part of the arrangement. Commercial terms should explain how any approved substitution affects pricing and capacity. Clear language reduces uncertainty when technical requirements evolve during the contract. The objective is not unlimited flexibility but a precise understanding of which options the buyer actually purchased.
Concentration Can Increase the Consequence of a Wrong Forecast
Capacity concentration can create exposure when too much future compute depends on one contractual relationship. Concentration does not automatically make an agreement undesirable. Working with fewer providers can reduce integration requirements and simplify infrastructure management. The risk grows when migration or workload reallocation becomes difficult within the required timeframe. Provider disclosures show how concentrated commercial relationships can become from the opposite side of these transactions. CoreWeave reported that Microsoft represented approximately 67% of its 2025 revenue. That figure measures customer concentration at CoreWeave, not supplier concentration for an AI buyer. Buyers need their own analysis covering providers, accelerator families, geographies, and contract periods. A consolidated capacity schedule can reveal commitments that may appear smaller when procurement teams examine each contract independently.
Multiple Reservations Can Create One Large Exposure
Individual reservations may look manageable when teams evaluate them separately. The combined commitment can present a different financial picture. One agreement may cover training capacity while another supports inference or product expansion. Their payment periods can overlap even when separate teams negotiated the contracts. Finance teams should therefore aggregate future capacity commitments across the organization. The schedule should show committed units, payment dates, prepayments, and contractual expiration points. It should also distinguish flexible capacity from amounts the buyer cannot readily reduce. That view gives management a clearer picture of future infrastructure spending. Without consolidation, separate procurement decisions can collectively create more committed capacity than the organization expects to consume.
The Reservation Needs a Downside Case Before Signature
A financial test should examine more than the scenario in which every demand assumption succeeds. Management can model slower workload growth, product delays, or lower-than-planned customer adoption. The model should calculate contracted payments under each scenario. It should also estimate consumed capacity and the potential amount of unused infrastructure. Existing contractual mechanisms may reduce some of that exposure. Teams should separate prepayments already made from future payments that remain avoidable under the agreement. Refund, credit, termination, and recovery rights also need consideration before treating prepaid amounts as unrecoverable. Finance can compare the resulting payment schedule with liquidity, operating cash flow, and other commitments. This analysis identifies how much demand can fall before the reservation becomes difficult for the organization to support economically.
Forecasts Need Review Points
A reservation decision should not disappear into the procurement system after signature. Workload forecasts need periodic comparison with actual consumption. Large differences between expected and measured demand can provide an early signal that the original capacity assumptions have changed. The same review can examine future payments that remain contractually committed. Infrastructure teams can contribute utilization data and updated workload schedules. Finance can assess the cash impact of remaining commitments. Procurement can identify contractual rights that might provide flexibility. Management can then evaluate new reservations using current demand evidence rather than relying entirely on forecasts created months earlier. Review points are particularly useful before an organization adds another long-term commitment to capacity it has already reserved.
Accounting Review Should Begin Before Procurement Ends
Accounting teams need detailed contract terms before they can classify sophisticated infrastructure arrangements correctly. Relevant provisions can include asset identification, substitution rights, payment obligations, termination options, and renewal terms. Agreements may also contain implementation, software, or equipment elements that require additional analysis. IFRS 16 ties lease identification to control over the use of an identified asset. The assessment includes economic benefits and the customer’s right to direct use. U.S. lease guidance applies comparable concepts involving identified assets and control. Cloud service arrangements can follow different accounting guidance when they do not contain a software license or lease. Procurement should therefore give accounting teams enough information to evaluate the arrangement before management authorizes a material commitment. Early review reduces the chance that commercial descriptions and accounting consequences produce different expectations.
Legal and Treasury Reviews Address Different Risks
Accounting classification represents only one part of the reservation decision. Legal teams need to determine what the executed agreement actually permits when circumstances change. Termination clauses may contain conditions that limit when a customer can use them. Service credits can also operate differently from cash refunds. Treasury teams need a separate view of when cash leaves the organization. Prepayments and fixed payment dates can influence liquidity before the corresponding services reach full utilization. Procurement needs to connect these findings with the commercial price and capacity schedule. Infrastructure teams can then determine whether the contractual configuration matches the expected workload. Bringing these views together gives management a clearer picture of both the accounting treatment and the economic commitment.
Balance-Sheet Risk Starts Before the Accounting Label Changes
The decisive point does not always coincide with the date an accountant records a new liability. Economic exposure can begin when a company commits enough future spending to reduce its ability to redirect cash elsewhere. That exposure does not make a capacity reservation inherently undesirable. Contracted compute may support product delivery, research schedules, operational continuity, or other business requirements. Problems develop when commitment size and rigidity move beyond the buyer’s confidence in the workloads expected to use that capacity. Management should examine utilization forecasts, cash timing, cancellation rights, and technical flexibility before signing. Accounting classification remains essential because it determines recognition and presentation under the applicable standards. It does not, however, determine whether the underlying commercial commitment will generate sufficient economic value. From a commercial perspective, risk increases when difficult-to-reduce payments remain in place while confidence in future capacity requirements declines.
A disciplined capacity strategy therefore treats reserved compute as more than an infrastructure allocation. Finance needs visibility into payments that remain fixed under different demand scenarios. Infrastructure teams need to know how much contracted capacity future workloads can realistically consume. Procurement needs to understand which contractual rights allow the organization to adjust its position. Accounting teams must determine how the arrangement should appear in the financial statements. Treasury must understand when the associated cash commitments become payable. Legal teams need clarity on termination, substitution, refund, and remedy provisions. When those functions share the same capacity schedule, management can distinguish a strategically useful reservation from an increasingly rigid financial commitment. The balance-sheet question then becomes part of a broader decision about how much future financial flexibility the organization is prepared to exchange for guaranteed access to AI infrastructure.