Skip to content

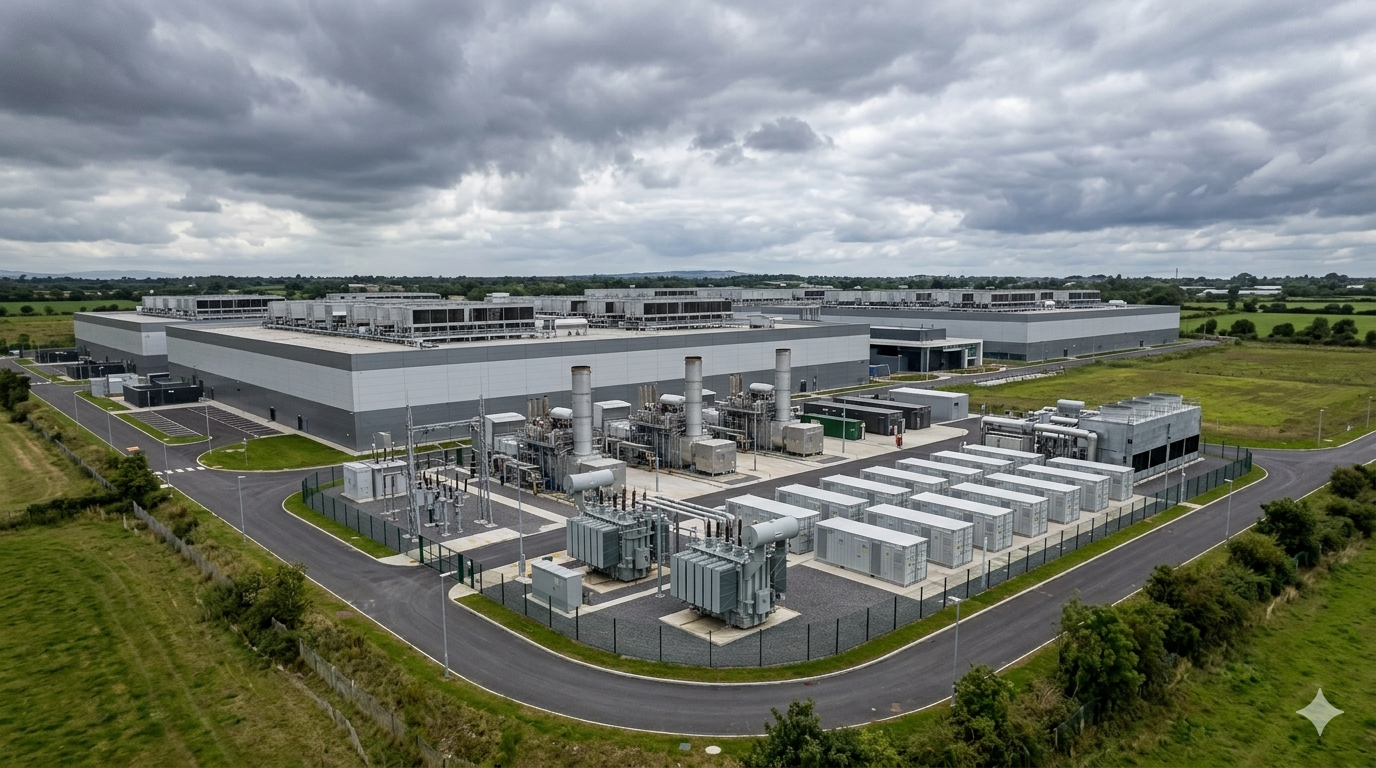
An AI data center can secure advanced accelerators, finalize its network architecture, and prepare its cooling infrastructure without knowing exactly when its electrical supply will become operational. The missing piece may sit far upstream, inside a steelmaking process that receives little attention in conversations about computing capacity. Grain-oriented electrical steel (GOES) forms the magnetic core of many power transformers, where its directional magnetic properties help transfer electricity between voltage levels while limiting energy losses. Transformer manufacturers cannot simply replace this specialized material with ordinary structural steel when they need to meet demanding electrical performance requirements. As AI infrastructure expands, developers must coordinate utility connections, substations, high-voltage equipment, medium-voltage distribution, and transformer deliveries before a site can support its planned computing load. This creates an important planning problem because semiconductor availability and electrical infrastructure readiness follow different industrial supply chains, with different production constraints and expansion timelines.
The familiar comparison between advanced computing and extreme ultraviolet lithography offers a useful way to understand this constraint, although the underlying technologies serve different purposes. EUV lithography enables manufacturers to print extremely fine features on advanced chips, while specialized electrical steel helps transformers convert and distribute the power those chips require. A shortage of either can restrict deployment, but additional accelerator shipments cannot compensate for a transformer that has not arrived or a substation that cannot energize its connected load. Furthermore, GOES production depends on tightly controlled metallurgical conditions that limit how quickly a mill can increase output without compromising magnetic performance. Buyers must therefore consider steel grades, approved suppliers, transformer designs, production slots, and delivery schedules alongside their semiconductor procurement plans. The practical implication is that AI capacity forecasts need to account for the upstream materials and electrical equipment required to turn announced megawatts into usable computing capacity.
Inside the Core: Why GOES Cannot Be Substituted
GOES derives its performance from a carefully engineered crystallographic texture that aligns the preferred magnetization direction of its grains with the direction of rolling. This alignment, commonly associated with Goss texture, allows magnetic flux to travel through the steel more readily than it would through material with randomly oriented grains. High-permeability grades, often called Hi-B, improve magnetic induction and reduce core losses through tighter control of grain orientation, microstructure, and processing conditions. Domain refinement can further reduce losses by modifying the magnetic domain structure, while thinner gauges help suppress eddy currents that develop as the magnetic field changes. Commercial products include grades around 0.23 millimeters thick, alongside thinner offerings at 0.20 millimeters and below, depending on the manufacturer and specification. These properties matter because transformer designers must balance efficiency, magnetic induction, operating temperature, physical dimensions, and manufacturing tolerances rather than select steel on thickness alone.
Replacing GOES with another magnetic material requires a complete assessment of the intended transformer application, not a simple material substitution. Non-oriented electrical steel suits magnetic circuits that experience flux in multiple directions, including many rotating electrical machines, but its magnetic characteristics do not automatically meet the requirements of conventional laminated power-transformer cores. Amorphous metal can deliver very low core losses and already serves as an alternative in suitable distribution-transformer designs, so claiming that it categorically fails in medium- or high-voltage equipment would be inaccurate. Its adoption depends on core geometry, magnetic properties, mechanical handling, manufacturing methods, transformer design, and the applicable performance requirements. However, a material change still requires engineering validation, production adjustments, and qualification rather than an assumption that another steel can immediately replace an established grade in every design.
The Mills Shaping AI Data Center Energization
The supply picture reveals a specialized industrial base with important producers across North America and Asia, although the available evidence does not establish that three mills control the entire global market. Cleveland-Cliffs is the sole domestic producer of GOES in the United States, making its Butler Works operation an important source for transformer manufacturers seeking American-produced material. In Asia, Baowu represents a major Chinese steelmaking group, while Nippon Steel and JFE Steel publish technical information on grain-oriented electrical steel products and manufacturing capabilities. These suppliers operate in a technically demanding market where a producer must deliver more than ordinary cold-rolled steel to meet transformer manufacturers’ magnetic-performance specifications. Their competitive position rests on process control, grade consistency, production capacity, technical expertise, and the ability to supply material that downstream manufacturers can convert into reliable transformer cores.
Production capacity alone does not reveal how much additional material a supplier can deliver to an urgent transformer order. Cleveland-Cliffs announced a $200 million investment at Butler Works intended to increase GOES production volume by up to 25 percent, demonstrating that domestic supply growth requires targeted capital investment rather than a simple increase in sales allocation. Asian producers also maintain differentiated grades and specialized production processes, which means that a buyer cannot treat every available ton as interchangeable with every other ton. Publicly available evidence cited here does not establish current utilization rates across the relevant mills or a standard qualification period for new GOES suppliers, since both depend on producer capabilities, product specifications, customer requirements, and validation procedures. A new producer generally needs to demonstrate repeatable metallurgical performance, coating quality, dimensional consistency, and compatibility with customer manufacturing processes before its material can become a dependable qualified supply source.
Why Steel Mills Scale Like Shipyards, Not Fabs
GOES manufacturing combines several tightly linked operations, including steelmaking, hot rolling, cold rolling, decarburization, high-temperature annealing, insulation coating, and finishing. Each stage helps establish the final material’s composition, texture, thickness, surface characteristics, and magnetic performance, so the production sequence must maintain control over the conditions that govern the evolving microstructure. Secondary recrystallization plays a particularly important role in developing the large, favorably oriented grains associated with high-performance grades. Domain-refined products may require additional processing that further improves magnetic behavior, adding another consideration to equipment capability and production scheduling. An ordinary sheet-steel line cannot automatically deliver high-performance GOES, because producing the required grade depends on specialized process controls, suitable equipment, and quality assurance, while conversion of existing facilities would require technical and commercial evaluation.
Capital investment can expand supply, but construction, equipment installation, process commissioning, yield stabilization, and customer qualification all influence when additional capacity becomes commercially useful. A newly installed production line does not immediately deliver its nameplate output in saleable premium grades, particularly when operators must establish stable metallurgical conditions and demonstrate repeatable performance. Consequently, a disruption at a concentrated production facility can affect downstream material availability, although its impact depends on inventories, qualified alternative suppliers, existing contracts, the duration of the interruption, and the availability of suitable grades. Transformer delivery queues can then compound the problem because manufacturers also need winding materials, insulation systems, fabrication capacity, testing resources, and other components to complete each unit.
The Global Capacity Ceiling Is Measured in Tons
AI infrastructure forecasting often begins with announced megawatts, planned campuses, accelerator shipments, and projected rack densities, but those figures describe demand rather than completed electrical capability. Each planned load must pass through an electrical supply chain whose transformers require suitable magnetic-core materials, manufacturing capacity, testing, transport, and integration into the wider power system. GOES tonnage can serve as one upstream indicator when analysts assess transformer production exposure, supplier concentration, and the ability of the electrical equipment market to support expanding computing demand, provided they interpret it alongside qualified-grade availability, transformer manufacturing capacity, and delivery data. Yet tonnage alone cannot establish how much AI capacity a region can energize because transformer designs consume different quantities of material and face different manufacturing and installation constraints.
A more useful infrastructure forecast will connect the steel mill’s production schedule to the transformer factory’s order book, the utility’s equipment requirements, and the developer’s commissioning plan. Analysts should monitor capacity expansions, planned maintenance, material-grade availability, supplier concentration, and delivery commitments while checking whether each indicator reflects announced intentions or verified production. They should also separate the risks associated with domestic sourcing from the risks associated with global availability, since imports can provide additional supply even as concentrated production creates exposure to trade disruptions and logistical constraints. Therefore, the relevant question is not whether steel has replaced semiconductors as the defining constraint on AI growth, but whether upstream electrical materials are receiving the same scrutiny as computing hardware in project planning.