Skip to content

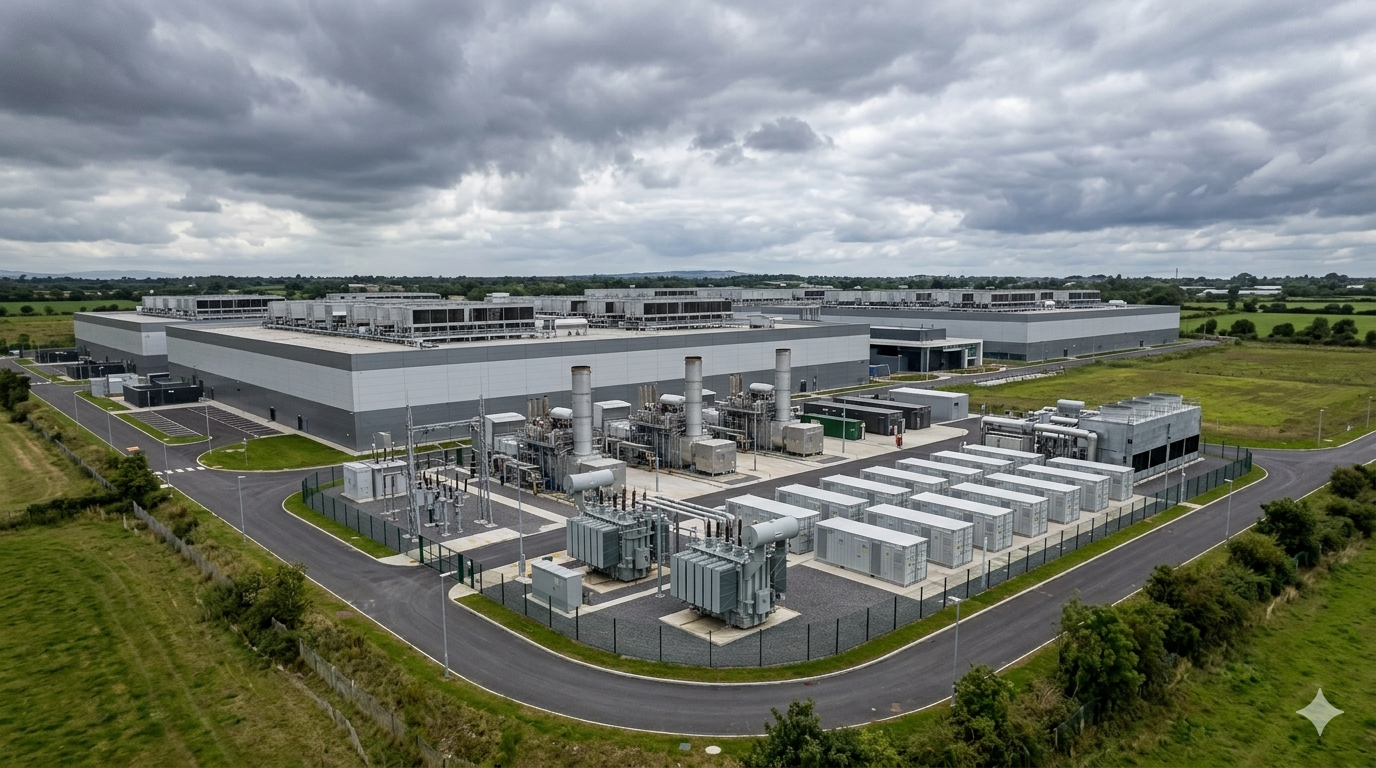
America’s data center expansion has become an economic development story that reaches far beyond the technology companies building the infrastructure, with new research from the U.S. Chamber of Commerce attempting to quantify the gains for workers, businesses, state governments, and surrounding communities. The report distinguishes the economic effects within a host state from the wider activity generated across national supply chains, although the distribution of those benefits depends on the model’s geographic boundaries and assumptions. Its estimates suggest that a single 50-megawatt data center can generate $680 million in state gross domestic product and support 5,220 jobs annually within its host state during a two-year construction period. Those figures capture an intensive phase of spending that draws on construction contractors, electrical specialists, equipment suppliers, engineering services, logistics providers, and other businesses needed to bring a complex facility online.
The report’s construction estimates also illustrate why data center economics require more than a narrow assessment of the buildings and equipment located within a project’s boundaries. A facility may occupy one county, yet its transformers, switchgear, backup power systems, cooling equipment, steel, cabling, and technical services can originate from suppliers spread across multiple states. That geographic reach explains the difference between the Chamber’s host-state figures and its broader national estimates, which account for economic activity outside the immediate project location. A balanced evaluation must identify both where the costs occur and where the benefits accrue, rather than treating national economic output as a guarantee of local gains. For investors and public officials alike, the relevant measure is not only the size of the economic footprint, but also how the modeled benefits are distributed, how long they last, and what evidence demonstrates their value to the host community.
Construction Creates a Powerful but Temporary Economic Surge
The Chamber estimates that every 50 megawatts of data center capacity supports or creates approximately 10,600 jobs and generates $1.6 billion in gross domestic product annually during the construction phase when it considers activity across the wider economy. These figures substantially exceed the host-state estimates because they include the businesses and workers that participate in the project’s extended supply chain, from manufacturing and transportation to professional services and specialized construction. The difference highlights a measurement challenge for communities considering new facilities, because the report’s national estimates include economic activity beyond the host state and do not establish how much of that activity any particular community retains. Construction creates a concentrated burst of demand, and the eventual scale of that activity depends on project design, procurement decisions, the availability of contractors, and the extent to which suppliers operate locally.
The two-year construction period also creates a planning challenge because the employment profile of a large data center changes significantly once the facility begins operating. Major building projects require substantial numbers of electricians, equipment installers, civil engineers, heavy-equipment operators, and other construction professionals, but many of those positions disappear when the work finishes. Construction employment remains economically important because workers earn wages, contractors purchase materials, and businesses receive revenue during the buildout, although the duration of these benefits varies by occupation and project. It does mean that officials should distinguish temporary job-years from permanent positions and avoid presenting every construction-related job as a continuing source of employment. A rigorous assessment should therefore distinguish temporary construction employment from continuing operational roles and separately track wages, local hiring, supplier contracts, and the public expenditure required to accommodate the facility.
A $450 Billion Economic Opportunity Comes With Constraints
The report applies its estimates to a much larger national expansion scenario, citing Goldman Sachs‘ estimate that the United States could add 13.6 gigawatts of data center capacity in 2026. If that buildout occurred and the report’s modeled economic relationships applied, the Chamber estimates that the activity would support approximately 2.9 million jobs, generate $450 billion in GDP, and produce $240 billion in family and household income during the year. These figures illustrate the potential scale of economic activity under the Chamber’s modeled scenario, but they do not represent guaranteed outcomes or independently verified measures of realized 2026 economic activity. When multiple projects compete for the same suppliers and contractors, limited availability can delay construction, raise costs, or shift some projected economic activity into later periods, depending on the severity and duration of the constraints.
The constraint problem also connects the economic case for data centers to the broader challenge of delivering power infrastructure at the pace developers require. A project can secure land and financing yet struggle to advance if grid connections, substations, transformers, or other electrical equipment remain unavailable on the required schedule. Delays can postpone planned hiring, defer supplier revenue, and shift expected tax receipts into later periods, although the size of these effects depends on each project’s schedule, procurement arrangements, and tax structure. Early coordination of power procurement, equipment orders, construction schedules, and workforce planning can help developers identify and manage delivery risks, although these measures cannot eliminate every constraint affecting the industry. For communities, the practical implication is that announced capacity should not be confused with completed construction, energized computing capacity, or realized economic activity.
Electricity Prices Remain Central to the Public Debate
Electricity costs represent one of the most sensitive questions surrounding data center expansion, particularly as utilities and regulators consider how to accommodate rapidly growing demand from digital infrastructure. The Chamber points to its separate analysis, Your Electric Bill Is Going Up, But Where You Live Decides How Much, which found that a greater concentration of data centers in a state does not lead to higher electricity costs. That finding reflects the Chamber’s analysis of statewide data center concentration and electricity prices; it does not establish that every data center has no effect on local power systems, utility investment requirements, or individual customer bills. Electricity prices and customer costs can reflect several factors, including generation availability, transmission capacity, utility investment, rate design, regulatory decisions, and the allocation of infrastructure costs among customer groups.
The policy challenge is to distinguish the economic value of new infrastructure from the way its costs and benefits reach different groups. Data centers can create jobs, expand the tax base, and support domestic supply chains, while their electricity requirements can also trigger substantial investment in generation, transmission, and distribution infrastructure. The extent to which existing customers benefit or face additional costs depends partly on tariff design, responsibility for infrastructure upgrades, and the assumptions regulators use when evaluating long-term electricity demand. Clear agreements and transparent cost allocation can help public officials evaluate how developers contribute to the infrastructure required to serve their facilities and how utilities distribute the remaining costs among customers. These questions matter not only for community relations but also for the credibility of economic impact claims, since public support becomes harder to sustain when residents believe they subsidize private development without receiving commensurate benefits.
The Next Phase of Data Center Growth Depends on Shared Value
Neil Bradley, Executive Vice President and Chief Policy Officer of the U.S. Chamber of Commerce, summarized the report’s argument by saying, “Communities that welcome data centres benefit long after construction ends through good-paying careers, new opportunities for local businesses, and revenue that helps support schools, roads, parks, and other local priorities.” His statement captures the central proposition behind the Chamber’s analysis: data center development can deliver benefits that continue beyond the initial construction boom, provided those benefits reach the communities hosting the infrastructure. Curtis Dubay, the Chamber’s chief economist, similarly says, “Construction supports thousands of jobs and hundreds of millions of dollars in economic activity, while ongoing operations create long-term benefits through wages, business spending, and tax revenue,” underscoring the distinction between immediate construction activity and recurring economic contributions.
Together, these statements present the Chamber’s view that data centers can contribute beyond their immediate technology function through employment, procurement, public revenue, and ongoing operations, while the scale of those benefits remains dependent on the assumptions behind the estimates. The report’s estimates provide a substantial economic case for examining that contribution, while its emphasis on planning and trust acknowledges that aggregate gains do not automatically resolve local concerns. Ultimately, America’s data center economy will be judged not just by how many megawatts developers build, but by whether the resulting prosperity proves measurable, sustainable, and fairly shared.