
Why Electricity Reporting Cannot Tell the Whole Sustainability Story
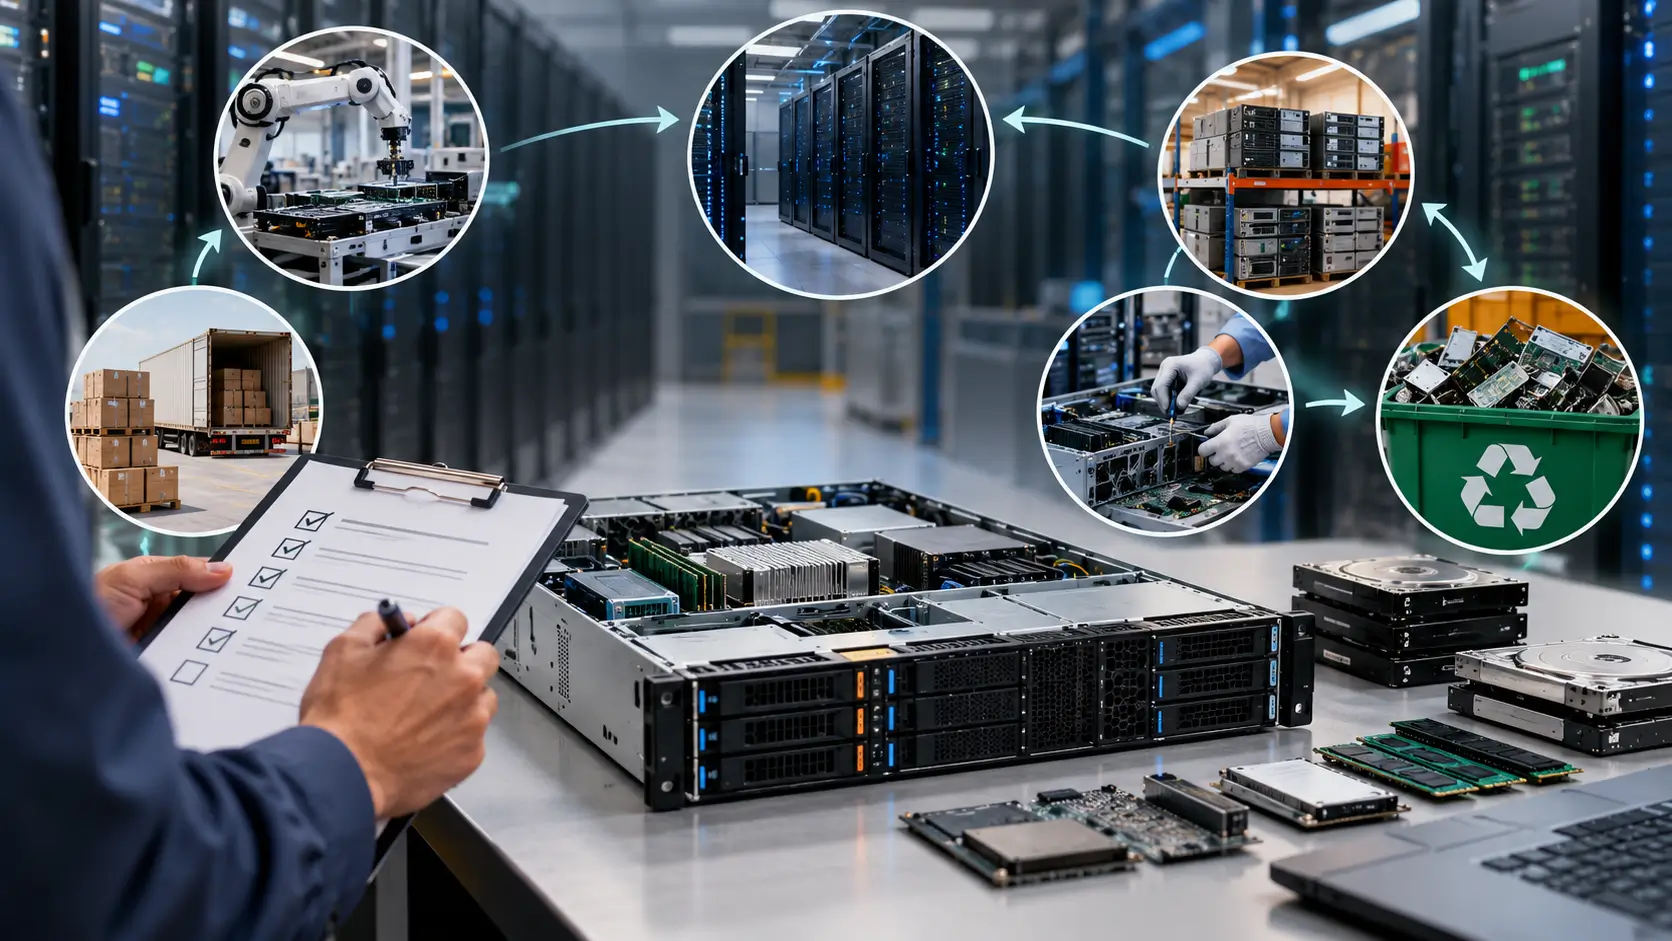
A data center can improve its electricity efficiency and still leave important environmental questions unanswered. A new server may consume less power during operation, yet its manufacture requires materials, component fabrication, assembly, and transportation. Equipment removed during an upgrade may also retain useful parts or support another workload. Its eventual destination determines whether those components remain useful or enter a recovery process. Electricity reports cannot independently establish what happened to these materials or why the organization replaced the equipment. Data center sustainability audits must therefore follow equipment throughout its lifecycle, connecting operational performance with procurement, maintenance, replacement, reuse, and retirement.

Electricity accounting remains essential because it explains a major part of the environmental impact associated with operating computing infrastructure. However, it cannot describe every impact created before equipment enters service or after it leaves the original deployment. Manufacturing creates upstream impacts, while maintenance and replacement introduce additional material requirements. Retirement then raises questions about repair, reuse, component recovery, and final treatment. These activities may occur in different reporting periods and fall within different accounting boundaries. A credible audit must connect these stages without treating every environmental impact as interchangeable.
The distinction matters when operators compare competing infrastructure decisions. Replacing an older system may reduce electricity consumption, but manufacturing the replacement also creates environmental impacts. Extending the existing system’s life may avoid an immediate purchase, although continued operation can increase power consumption or maintenance requirements. Neither option guarantees the lowest overall environmental impact in every situation. The outcome depends on workload demands, equipment condition, operating efficiency, and the alternatives available. Sustainability reporting should make these trade-offs visible instead of treating one indicator as proof of overall progress.
Equipment Procurement Must Establish the Environmental Starting Point
Procurement establishes the first opportunity to create a traceable equipment history. Purchasing records identify the products entering service, their configurations, and the commercial terms governing the transaction. Lifecycle auditing requires additional information about repairability, component availability, maintenance support, and environmental documentation. These records become particularly important when specialized hardware may need replacement or refurbishment later. Buyers should distinguish product-specific evidence from general sustainability statements. A claim about one component or manufacturing process does not necessarily describe the complete system.

Product documentation must match the equipment purchased
A useful equipment register identifies the product, configuration, acquisition date, deployment destination, and supporting documentation. These details allow auditors to trace changes throughout the asset’s service life. Supplier lifecycle assessments can provide useful information when their boundaries and assumptions match the product under review. However, a declaration for a general product family may not accurately represent every configuration. Different processors, memory arrangements, storage devices, and power supplies can change the equipment being assessed. Procurement teams should retain the documentation needed to establish which product the evidence actually covers.
The distinction between measured information and estimated results also matters. A lifecycle assessment depends on its scope, data quality, assumptions, and treatment of relevant stages. Its conclusions cannot automatically be transferred to another product or operating scenario. Environmental declarations can support comparisons, but only when the documents use suitable and sufficiently comparable methods. When suppliers cannot provide detailed evidence, buyers should record the gap rather than assume a favorable environmental outcome. The organization can then decide whether an estimate is appropriate or whether the uncertainty prevents a meaningful comparison.
Procurement records should also capture substitutions and configuration changes that occur before delivery. The equipment ultimately installed may differ from the original purchase specification. That difference can affect whether the available environmental documentation remains relevant. Buyers should preserve the identifiers needed to connect supplier information with the delivered system. They should also establish a process for requesting updated documentation when a material substitution changes the assessed product. These controls make environmental claims easier to verify and reduce the need to reconstruct purchasing decisions later.
Repairability and support influence equipment life
The ability to repair or upgrade equipment can influence whether an organization replaces an entire system or preserves useful components. Accessible parts, technical documentation, available spares, and continuing software support can make maintenance more practical. However, repairability depends on the product’s design and intended use. A component may be physically replaceable but no longer supported by suitable firmware or software. Another system may remain functional but require maintenance that creates unacceptable operational risk. Auditors should examine these constraints before concluding that continued use remains practical.
Repairability does not mean that every asset should remain in service indefinitely. Equipment may become unsuitable because of security requirements, compatibility limitations, reliability concerns, or unavailable replacement parts. In other cases, the system may continue operating effectively after a limited repair. The audit should document the technical circumstances rather than assume that repair always offers the best environmental outcome. Procurement teams can improve future decisions by recording support arrangements and expected maintenance options. Later reviews can then establish whether those arrangements remained available throughout the equipment’s useful life.
The same reasoning applies when an organization evaluates upgrades during procurement. A system that supports component replacement may offer different lifecycle options from one that requires complete replacement. Yet modular construction alone does not establish that the equipment will remain useful longer. Spare-part availability, software support, operating requirements, and compatibility also influence the result. Buyers should evaluate these characteristics alongside performance, security, and cost. This approach creates a more realistic basis for comparing equipment options without promising environmental benefits that the available evidence cannot establish.
Deployment Records Must Show How Equipment Creates Value
A purchase record cannot establish whether a server delivered the service that justified its acquisition. Equipment may wait for application readiness, remain in reserve, or move between workloads. Power and cooling constraints can also prevent the intended configuration from entering service. These situations have different implications for lifecycle performance and should not receive identical treatment. An asset register should connect each system with its configuration, location, intended workload, and material changes. Auditors should then examine whether periods of inactivity reflect legitimate operational needs or avoidable planning problems.
Establish a baseline that follows the physical asset
The initial deployment record should identify equipment clearly enough to support future maintenance, transfers, and retirement decisions. Where a server contains replaceable components, the record should distinguish its original configuration from later changes. A memory module may leave service before the chassis does. A chassis may also remain useful after its original configuration becomes unsuitable. Commissioning records, acceptance tests, warranty information, and deployment documents help establish the asset’s starting condition. Auditors should connect these records with later changes rather than rely on a single inventory snapshot.
The baseline should also identify the infrastructure needed to operate the equipment. A server depends on power delivery, networking, cooling, and appropriate software configuration. Its practical service life may therefore depend on more than the physical condition of its components. A system moved to another environment may require changes before it can resume useful operation. The audit should record material changes without treating every routine technical action as a separate sustainability event. The objective is to preserve enough information to explain the asset’s history and support significant lifecycle decisions.
Asset identification becomes particularly important when teams replace components without replacing the complete system. If records track only the chassis, auditors may struggle to determine which components entered service or when replacements occurred. Component-level records can clarify whether a part remained in use, moved elsewhere, or entered recovery. They can also help establish whether the organization retained useful equipment during a wider upgrade. The appropriate level of detail depends on the asset and the materiality of the decision. The register should provide sufficient traceability without creating unnecessary administrative work.
Interpret utilization in its operational context
Low utilization does not automatically mean equipment has no value. Some systems must remain ready for recovery operations, variable demand, or intermittent workloads. Other systems remain underused because teams purchased capacity before applications became ready. Auditors should examine utilization alongside availability requirements, workload schedules, maintenance restrictions, and deployment history. This analysis can reveal whether the organization needs reserve capacity, better workload allocation, or a retirement decision. It should distinguish legitimate standby equipment from systems that remain powered without a clear operational purpose.
Utilization becomes more informative when teams connect it with the work equipment actually performs. A server with low average activity may support an essential recovery function. Another system with similar activity may remain idle because its intended application never entered production. Those situations should not receive the same interpretation. Auditors should also consider whether consolidating workloads would create new reliability, security, or capacity constraints. Where evidence identifies avoidable inactivity, the organization can investigate procurement timing and deployment planning.
The audit should avoid treating a single utilization measure as proof of environmental performance. Low utilization does not independently establish waste, just as high utilization does not prove that a system operates efficiently. The assessment must consider the workload, equipment condition, and service requirements. It should also identify whether unused capacity can support another workload without requiring substantial changes. Where reserve capacity remains necessary, the organization should document its purpose. This context helps decision-makers distinguish avoidable inactivity from equipment that performs a legitimate operational role.
Hardware Upgrades Need a Lifecycle Comparison
Hardware refreshes often promise improved performance, support for new workloads, and better energy efficiency. However, their environmental implications depend on more than the replacement’s specifications. Manufacturing the new system introduces upstream impacts, while installation may require changes to networking, power delivery, and cooling. The displaced equipment then creates a separate decision about reuse, refurbishment, component recovery, or retirement. An audit should document the requirement that prompted the upgrade and compare realistic alternatives. This comparison provides a stronger basis for balancing environmental considerations with performance, reliability, security, and operating cost.
Compare the complete replacement pathway
A meaningful comparison begins by defining the workload requirement and identifying configurations that can satisfy it. The assessment should consider the existing system’s electricity consumption, remaining useful life, maintenance needs, and ability to support the application. It should also examine the replacement’s manufacturing impacts and operating characteristics. Another important question is whether the new system replaces existing capacity or enables additional computing demand. These outcomes create different environmental questions. Auditors should document the assumptions and boundaries used in the comparison.
The alternatives should provide comparable computing services wherever possible. Comparing systems with different workloads or performance requirements can produce conclusions that reflect differences in function rather than environmental advantages. Teams should identify important differences in reliability, capacity, and operating conditions. They should also establish whether the replacement will increase total computing demand. Where the evidence cannot support a reliable comparison, the organization should explain the limitation. A documented decision can still be useful without a single numerical result.
The audit should also consider the equipment’s remaining service potential. A system that still meets its workload requirements may not need immediate replacement. Another system may require replacement because it cannot meet security or reliability requirements. These situations demand different responses. The assessment should document the technical reason for the decision and the available alternatives. This makes replacement decisions more defensible and prevents advertised efficiency improvements from becoming unsupported claims about total lifecycle performance.
Follow displaced equipment after installation
The arrival of replacement hardware should trigger an update to the record for the equipment it displaces. A retired server may support a lower-demand workload, provide spare components, enter refurbishment, or proceed to recycling. Each pathway requires evidence appropriate to the claim. A transfer receipt or resale invoice establishes movement, not necessarily continued productive use. Auditors should record the destination, equipment condition, transfer date, and available confirmation of subsequent deployment. If reuse is impractical, the audit should preserve the technical or security reasons.
Displaced equipment also needs a clear status while the organization decides what to do with it. Systems waiting for inspection should not remain indefinitely in an inventory category that implies they are ready for deployment. Asset managers should record whether the equipment remains functional, requires repair, has a confirmed destination, or has entered an approved retirement process. These distinctions help prevent stored hardware from being overlooked during procurement. They also provide a more reliable basis for evaluating reuse. When a transfer does not lead to further productive use, the organization should report the verified outcome accurately.
The record should remain open until the organization establishes the equipment’s next status. A transfer to another location may lead to successful deployment, further maintenance, or eventual retirement. Each outcome affects the interpretation of the original replacement decision. Where downstream information is unavailable, the audit should state that limitation rather than assume the best outcome. This discipline makes lifecycle reporting more credible and helps management distinguish planned reuse from verified reuse. It also creates a clearer basis for improving future upgrade procedures.
Cooling Infrastructure Must Follow the Same Lifecycle Principles
Cooling equipment deserves a place in lifecycle auditing because pumps, heat exchangers, fans, compressors, filters, and fluid distribution components require materials and maintenance throughout their service lives. These systems also interact directly with computing hardware. A server upgrade can trigger changes to cooling capacity, component compatibility, and operating conditions. A project may preserve the computing equipment while replacing cooling components. Another project may require broader changes because the existing arrangement cannot support the intended workload. Auditors should connect cooling inventories with the equipment they support and document the reasons for major modifications.
Track cooling components through maintenance and replacement
A cooling-system register should identify major components and preserve records of installation, repair, replacement, and retirement. Replacing a pump differs from replacing an entire cooling assembly, even when both activities appear as maintenance expenditure. The audit should establish which components remained in service and which parts technicians removed. It should also record whether removed equipment entered repair, refurbishment, recovery, or disposal. Maintenance records involving fluids or refrigerants should address handling and recovery where relevant. Repeated component failures deserve additional review because they may indicate an underlying operating or maintenance problem.
Cooling maintenance records should distinguish routine servicing from changes that materially alter the system. Replacing a worn component may preserve the wider assembly. A change in cooling architecture may require new distribution equipment, controls, or connections. Those decisions have different lifecycle implications and should not be grouped together merely because both occur during maintenance. The audit should identify why each change occurred and what happened to the parts removed from service. Teams should also follow relevant handling requirements for fluids and refrigerants. This information helps explain the environmental implications of maintaining cooling capability.
Maintenance can preserve useful equipment, but repeated repairs may eventually become impractical. The decision depends on the system’s condition, component availability, operating requirements, and reliability. Auditors should examine recurring failures and determine whether they reflect a broader technical problem. They should also document whether the organization considered repair, component replacement, or full-system replacement. These records can help teams improve maintenance planning and avoid replacing equipment without a clear technical reason. They also prevent maintenance activity from being treated as proof of environmental improvement on its own.
Assess cooling changes alongside computing changes
Cooling and computing decisions should not proceed as unrelated projects when one system determines the requirements of the other. Higher-density hardware may require different thermal management, fluid distribution, heat rejection, or power delivery. A cooling limitation may also prevent otherwise usable servers from operating in their intended configuration. An audit should identify the technical reason for each major change and establish which existing components remain suitable. It should distinguish necessary capacity expansion from replacement driven by compatibility problems or incomplete planning. This evidence supports coordinated infrastructure decisions.
A cooling upgrade should be assessed against the operating conditions the computing system actually requires. The technical case may involve reliability, maintenance access, equipment compatibility, or changes in workload characteristics. Auditors should establish whether the existing arrangement could meet those requirements through repair or modification. Where replacement is necessary, the record should explain which components require retirement. It should also identify whether removed equipment remains suitable for another use. This system-level assessment helps teams understand lifecycle consequences before committing to a particular design or procurement path.
The assessment should also consider whether changes to one system create additional requirements elsewhere. A revised cooling arrangement may require new controls or distribution components, while a server replacement may make existing cooling equipment unsuitable. These dependencies can affect procurement timing, installation work, and the retirement of existing assets. The audit should document the important relationships without assuming that every project creates the same environmental burden. Teams should compare realistic options and record the evidence behind their decisions. This approach makes infrastructure planning more transparent and reduces the risk of overlooking equipment that could remain useful.
Relocation Can Extend Useful Life, but Only When the Destination Is Ready
Moving equipment to another computing environment can preserve its value when the destination can use the system effectively. However, relocation introduces transportation, handling, inspection, configuration, and testing requirements. A server that works reliably in one environment may not fit another environment’s power, cooling, networking, security, or software requirements. Equipment can also remain idle after transfer when the receiving workload is delayed. The audit should therefore treat relocation as a lifecycle event with a documented purpose. This record helps determine whether the move extended productive service or merely postponed retirement.
Document the reason for each material transfer
A relocation record should explain why the equipment moved, what role it is expected to perform, and which technical assessments supported the decision. Workload changes, consolidation, available rack space, power constraints, and cooling requirements can all create legitimate reasons to transfer equipment. The audit should establish the asset’s condition before departure and after installation. This is particularly important when transport damage, missing components, or configuration changes affect its remaining service potential. A transfer without a confirmed deployment plan may leave equipment unused at its destination. Teams should connect relocation approvals with destination readiness and the expected operational purpose.
Relocation decisions should also account for compatibility with the receiving environment. Technical teams may need to verify software support, component compatibility, security requirements, and access to replacement parts. If those conditions cannot be met, moving the equipment may simply postpone retirement while adding handling work. The audit should preserve the assessment that explains whether the transfer remains justified. If the destination changes after approval, the record should reflect the revised plan. This makes relocation a verifiable asset-management decision instead of an administrative movement that disappears from the sustainability record.
The equipment’s original purpose should remain visible throughout the transfer process. A system moved for a specific workload may not be suitable for a different application without additional configuration or testing. The audit should document material changes in purpose and identify whether the receiving workload remains viable. Where the transfer fails to produce a useful deployment, the organization should record the outcome and decide whether another pathway is appropriate. This information helps teams evaluate relocation decisions more accurately. It also improves future planning by showing which transfers resulted in continued service and which encountered avoidable constraints.
Account for destination compatibility and installation work
A successful relocation requires more than delivery because engineers must establish that the destination can support the equipment safely and reliably. The work may involve inspection, firmware validation, configuration changes, network testing, power compatibility checks, and confirmation that cooling conditions meet operating requirements. The audit should document significant repairs, replacement parts, packaging, transportation, and testing where these activities affect the assessment. It should also record whether the system entered productive service or remained in a maintenance queue. These details provide evidence about relocation’s practical effectiveness. They can also show whether future transfers need stronger readiness checks.
The receiving team should confirm the equipment’s status after installation. Delivery alone does not establish that a server passed testing or became available to its intended workload. Where a system fails acceptance checks, the record should explain whether technicians repaired it, returned it to storage, or redirected it toward retirement. These outcomes matter because relocation preserves equipment value only when the system remains suitable for a useful role. The audit should not assign a verified environmental benefit when the evidence establishes only that the equipment moved. A clear post-transfer record strengthens lifecycle reporting and helps technical teams improve future relocation decisions.
Relocation also creates an opportunity to reassess the equipment’s remaining service potential. The receiving environment may support the system for longer than the original deployment, or it may reveal limitations that make further use impractical. Auditors should record the condition and role of the asset after the move. They should also retain evidence of significant repairs and configuration changes. Where the system returns to service, the record should identify its new deployment purpose. This provides a stronger basis for evaluating whether relocation extended useful life rather than simply changing the equipment’s location.
Reuse, Refurbishment, and Recycling Need Separate Evidence
Reuse can preserve equipment value and reduce demand for new manufacturing when a second user obtains useful service from an existing system. However, an organization cannot establish that outcome merely by recording that retired equipment left its premises. The equipment may remain in storage, require extensive repairs, or reach a recipient who soon discards it. Refurbishment, component recovery, recycling, and disposal also represent different outcomes. Each pathway preserves a different amount of the equipment’s original function and material value. Auditors should identify the actual pathway and retain evidence appropriate to the claim.
Confirm that reused equipment enters a useful second life
The strongest evidence of reuse connects an asset to a credible destination and establishes that it remains suitable for a useful purpose. Internal transfers can be documented through receiving-team confirmation, updated configuration records, and evidence of deployment. External resale creates greater uncertainty because the original owner may lack access to the buyer’s subsequent records. The audit should distinguish a verified transfer from a claim that the equipment continued operating or displaced a new purchase. Refurbishment reports and transfer documents can strengthen the record. Where the subsequent outcome remains unknown, the organization should report the transfer accurately and leave the broader environmental benefit unquantified.
A credible reuse program also needs a process for evaluating equipment condition before another deployment. Technicians should assess whether the system meets the receiving workload’s performance, reliability, compatibility, and security requirements. The assessment should consider whether replacement parts remain available and whether the system can receive necessary software and firmware support. Where extensive repairs are required, the organization should evaluate whether refurbishment remains practical. These checks establish whether the proposed second use is technically credible. The audit can then distinguish an approved reuse plan from a verified outcome.
The organization should also retain evidence showing whether the receiving user actually put the equipment to work. A shipment confirmation does not establish that a system became operational. If the equipment remains in storage or enters another retirement process, the record should reflect that outcome. This does not mean the original transfer lacked value, but it limits what the organization can claim about environmental benefits. Auditors should state these limits rather than assume that resale automatically prevents new manufacturing. This approach preserves the distinction between a documented activity and a verified environmental result.
Preserve technical and environmental controls during refurbishment
Refurbishment requires a documented assessment of condition, repairability, security, and compatibility with the intended workload. Technicians may replace failed components, inspect assemblies, update firmware, and test performance. The audit should record the work performed, parts replaced, final condition, and intended destination. It should also examine whether the process required extensive component replacement. Restoring a system with limited intervention differs from rebuilding it around newly manufactured parts. Data sanitization and configuration verification remain necessary when equipment changes ownership or enters another operating environment.
Refurbishment records should distinguish the original equipment from components introduced during restoration. This allows auditors to identify which parts remained in use and which required replacement. The receiving organization should retain the available test results and acceptance documentation. If the equipment fails testing or cannot receive necessary software support, the audit should record the resulting decision. The organization should also preserve records for components removed during refurbishment. These controls provide a clearer account of the process and prevent the number of repaired assets from becoming a substitute for evidence of useful service.
The environmental implications of refurbishment depend on the equipment, the work required, and the alternative that would otherwise have been chosen. A successful repair may preserve useful hardware, but the audit should not automatically treat every repair as an environmental improvement. Extensive replacement work may introduce additional material demand, while an unsuccessful refurbishment may lead to further handling and eventual retirement. Teams should document the actual outcome and explain material limitations. Where evidence does not support a broader environmental conclusion, reporting should focus on the verified technical result. This makes refurbishment reporting more transparent and useful for future equipment decisions.
Retirement Must Include Secure Handling and Material Recovery
When equipment can no longer support a suitable workload, the audit should establish what happens to the asset and its recoverable materials. Servers contain metals, circuit boards, plastics, storage devices, power supplies, and other components. These materials may require different treatment pathways. The final outcome depends on equipment condition, recovery processes, and the handling of materials that cannot be reused. A disposal certificate can provide important evidence, but it may not establish the ultimate destination of every component. Organizations should preserve the asset’s identity, receiving party, transfer conditions, and available treatment documentation.
Evaluate repair and recovery before final retirement
A retirement assessment should establish whether equipment remains repairable, whether components can support other systems, and whether a suitable reuse pathway exists. This process should not force organizations to refurbish every asset. Poor condition, unsupported software, security restrictions, and excessive repair requirements can make continued operation impractical. The audit should document the equipment’s condition and explain why the selected pathway offers a reasonable balance. When technicians recover components, the record should identify the parts and their destination. Equipment sent for recycling should have separate documentation identifying the receiving party and available treatment evidence.
Retirement procedures should distinguish equipment that has reached the end of its useful life for one operator from equipment that has no remaining practical use. A server may no longer satisfy its original workload but could support a less demanding application. Another system may have become unsuitable because essential parts or software support are unavailable. The audit should document the technical reason for retirement and the alternatives considered. Where reuse is not appropriate, the organization should identify the available recovery route. If the downstream outcome cannot be verified, the report should state that limitation.
The retirement decision should also establish whether components can be recovered without creating unacceptable technical or security risks. A working part may have little practical value if compatible systems no longer exist. Another component may remain useful but require testing before redeployment. Auditors should record the condition of recovered parts and whether they entered an approved inventory. They should distinguish components awaiting assessment from parts confirmed suitable for reuse. This helps prevent unverified inventory from being counted as successful recovery.
Integrate data security with environmental recovery
Storage devices may remain technically functional even when an organization cannot transfer them for reuse until data sanitization is complete. The audit should connect sanitization records with physical asset identifiers. It should document whether each device remained suitable for reuse, required additional treatment, or proceeded to destruction. When destruction becomes necessary, the organization should preserve evidence of the method used and subsequent handling. Secure destruction does not automatically establish responsible recycling. The remaining materials still require appropriate documentation.
Data security and environmental recovery should be treated as connected responsibilities. The audit should establish which devices require sanitization and which approved procedures apply. It should retain evidence confirming completion before equipment moves to another owner or treatment provider. Where the organization destroys a device because it cannot verify secure reuse, it should document the reason. The record should also identify the party responsible for subsequent handling. This creates a clearer chain of custody and supports accurate reporting.
The same principle applies to equipment that contains sensitive configuration information or components subject to specialized handling requirements. Retirement procedures should establish who approves the transfer, who verifies security controls, and who retains the relevant documentation. If a receiving party cannot provide the evidence required to support a reuse claim, the organization should avoid describing the outcome as verified reuse. Where the final treatment remains uncertain, the audit should make that limitation explicit. These controls protect information while preserving legitimate opportunities for reuse and recovery.
Carbon Accounting Must Reflect Equipment Lifecycles Without Double Counting
Equipment lifecycle audits should connect asset records with greenhouse gas accounting while preserving the distinction between operational emissions and value-chain emissions. Electricity consumed during operation generally contributes to indirect energy emissions when an organization purchases that electricity. Manufacturing servers and other capital assets creates upstream emissions. These categories answer different questions and should not be combined without a clearly defined method. An organization can reduce operational emissions while purchasing more equipment. It can also extend equipment life while increasing electricity consumption. Auditors should document boundaries, assumptions, data sources, and the treatment of relevant lifecycle stages.
Separate manufacturing impacts from operational electricity
Manufacturing impacts arise before equipment begins delivering useful computing service, while operational electricity emissions accumulate as equipment runs. A lifecycle assessment can examine both stages, but the audit should retain the underlying evidence. Estimates with different boundaries should not be treated as directly interchangeable. Supplier-specific product information may provide useful detail, although its reliability depends on the assessed product and the assumptions used. Where product-specific evidence is unavailable, an organization may need an appropriate estimation method. The audit should explain its limitations rather than present the estimate as a direct measurement.
The accounting process should establish whether an assessment covers the complete product, selected components, manufacturing alone, or a broader lifecycle. A result that excludes transportation, maintenance, use, or end-of-life treatment cannot represent all those stages. Estimates from different product categories may also lack comparability when their assumptions differ. Auditors should preserve the method used and identify material exclusions. When better supplier information becomes available, the organization should determine whether earlier results require review. This practice improves transparency and helps distinguish methodological changes from actual environmental improvements.
Operational reporting requires similar discipline. Published efficiency specifications do not necessarily represent the performance of equipment under every workload. Actual electricity consumption depends on configuration, utilization, operating conditions, and the work performed. The audit should use reliable operational data where available and document any estimation method. It should also establish the reporting boundary so that comparisons remain meaningful. These controls allow decision-makers to examine manufacturing and operational impacts together without merging distinct categories into a misleading result.
Avoid unsupported claims about emissions avoided through reuse
Reuse can reduce demand for new manufacturing when a second user obtains useful service from existing equipment that would otherwise have been replaced. However, an emissions-avoidance claim requires a defensible comparison with a plausible alternative. Evidence that equipment changed ownership is not sufficient on its own. The assessment should consider whether the receiving user would otherwise have purchased new equipment. It should also establish whether the reused system entered service and how its operating characteristics affect the comparison. When these details remain unknown, the organization should describe the verified transfer and leave the broader environmental benefit unquantified.
The same caution applies to claims about extending equipment life or recovering components. These outcomes may be beneficial, but their significance depends on the actual equipment pathway. A component placed in storage has not necessarily displaced a future purchase. Equipment transferred to a recovery provider has not necessarily yielded a verified material recovery outcome. Auditors should distinguish completed activities from intended outcomes. They should also document assumptions about what would have happened without the intervention. This approach prevents uncertain estimates from becoming overstated sustainability claims.
Comparisons should also avoid counting the same environmental benefit more than once. For example, an organization should not claim a manufacturing impact avoided through reuse without establishing the accounting boundary and ensuring that the same benefit has not been attributed elsewhere. Where multiple parties participate in a transfer, their respective claims may require clarification. The audit should document the method used and identify the party responsible for each reported outcome. When the available evidence cannot resolve the question, the report should explain the uncertainty. This makes environmental reporting more defensible and supports fair comparisons between equipment strategies.
Supplier Evidence Determines How Much of the Lifecycle Can Be Verified
An audit can trace equipment accurately within a data center and still lack evidence about environmental impacts created before procurement. Manufacturers and component suppliers hold much of the information needed to assess material sourcing, manufacturing processes, assembly, transportation, and product design. Buyers may receive only partial information when a system contains components sourced through several supply-chain layers. This gap requires organizations to distinguish verified product information from estimates and assumptions. Procurement requirements can improve the available evidence by specifying which disclosures suppliers should provide. A consistent record can help identify equipment categories that need better documentation.
Request evidence that matches the purchased configuration
Supplier environmental information becomes more useful when it relates to the actual product configuration. A server assembled with different processors, memory, storage devices, and power supplies may have a different manufacturing profile from another system with a similar product name. The audit should retain model and configuration identifiers that connect supplier documentation with the equipment purchased. Where a supplier provides an environmental product declaration or lifecycle assessment, the record should preserve its scope, assumptions, date, and limitations. If configuration-specific information is unavailable, the organization should document the gap. It should then explain the estimation method rather than present generic information as a direct measurement.
The organization should also establish how supplier information will remain connected to equipment after delivery. Product substitutions, revised configurations, component replacements, and manufacturing changes can affect whether the original documentation still applies. Procurement teams should preserve the information needed to determine which records relate to the delivered equipment. They should also establish whether a material change requires additional assessment. When suppliers cannot provide a complete history, the audit should identify the missing information and explain its implications. This record can guide future purchasing requirements and supplier engagement.
Supplier information should not be treated as equally reliable merely because it appears in a formal document. Auditors need to understand the assessed product, the method used, and the limits of the available evidence. A declaration may provide useful information for one purpose while remaining unsuitable for another comparison. The audit should preserve those distinctions and avoid assigning precision that the underlying data cannot support. Where assumptions materially influence a result, they should remain visible in the reporting record. This improves transparency and reduces the risk of overstating the certainty of lifecycle claims.
Contractual requirements can improve traceability
Procurement contracts can establish expectations for equipment documentation, spare-part availability, repair support, component substitutions, and returned hardware. These terms matter because sustainability teams cannot reconstruct a complete lifecycle history if suppliers change configurations without preserving relevant records. Contracts can also specify how suppliers should document refurbishment, warranty replacements, and equipment returns. Buyers should distinguish mandatory disclosures from optional information and define the evidence that will satisfy each requirement. Supplier commitments should not automatically count as proof that a lifecycle outcome occurred. The audit still needs records showing how equipment was handled in practice.
Contractual terms work best when they define practical evidence requirements. Buyers can specify product identifiers, documentation formats, change notifications, and transfer records. They can also clarify which party must retain records for warranty replacements, refurbished products, or returned components. The organization should assess whether the requested information can reasonably be supplied. It should also establish a process for resolving gaps. These measures connect purchasing decisions with later maintenance and retirement activities without assuming that a stated policy guarantees an environmental outcome.
Contracts should also support continuity when equipment changes ownership or reaches the end of its support period. Relevant documentation may include repair instructions, spare-part information, component substitutions, and records for returned hardware. The exact requirements will depend on the product and transaction. Auditors should examine whether the agreed information was actually supplied and whether it remains relevant to the equipment under review. Where documentation is missing, the organization should record the limitation. This combination of contractual expectations and operational verification makes lifecycle reporting more reliable.
Audit Governance Must Connect Sustainability, Engineering, and Procurement
Equipment lifecycle auditing requires coordination because no single team holds every record needed to establish an asset’s environmental history. Procurement teams manage supplier documentation, while technical teams maintain configuration and repair records. Operations teams hold deployment information, and asset managers oversee transfers and retirement. Sustainability teams must connect these records with the organization’s reporting boundaries. A useful audit process assigns responsibility for maintaining the equipment register and approving material changes. It should also establish how teams investigate discrepancies and distinguish measured results from estimates.
Create an evidence trail for every material decision
A lifecycle audit becomes easier to verify when each material event leaves a consistent record linked to the affected asset. Procurement should establish the initial equipment identity and retain available product documentation. Deployment records should show the installed configuration and intended workload. Maintenance teams should document repairs, upgrades, component replacements, and material operating changes. Asset managers should record transfers, refurbishment, and retirement decisions. The audit should preserve downstream evidence when the organization claims that equipment entered reuse or recycling. This approach gives reviewers a traceable sequence of events and helps identify weaknesses before they affect published claims.
Recordkeeping should remain proportionate to the decision being assessed. Routine actions may require less documentation than a complete hardware replacement or major cooling modification. Organizations should define which changes require formal review and who must approve the resulting records. They should also establish how long supporting information remains available. When equipment moves between locations or changes ownership, its history should remain traceable. If evidence is missing, teams should document the gap rather than reconstruct an asset history from assumptions. These controls maintain a usable record without creating unnecessary administrative work.
The audit should also establish how different systems identify the same physical asset. Purchasing, maintenance, inventory, and retirement records may use different identifiers. Without a reliable connection, auditors may struggle to establish whether records describe the same equipment. Organizations should define a consistent method for linking those records and resolving conflicts. They should preserve the evidence used to resolve material discrepancies. This makes the audit easier to repeat and reduces uncertainty when equipment changes configuration or location.
Use findings to improve future equipment decisions
The value of a lifecycle audit extends beyond confirming whether past records are complete. Its findings can reveal where purchasing, deployment, maintenance, and retirement practices create avoidable environmental burdens. Repeated gaps in supplier documentation may indicate a need for stronger procurement requirements. Recurring periods of unused hardware may point to weaknesses in deployment planning or workload allocation. Frequent replacement of otherwise serviceable components may justify reviewing repair support and spare-part availability. Management should prioritize improvements according to the importance of each issue and the quality of available evidence. This approach helps turn audit findings into practical changes.
Findings should also inform future infrastructure projects. If usable equipment repeatedly becomes stranded after upgrades, teams can improve compatibility checks and plan for displaced assets before approving replacements. If maintenance support ends before equipment becomes technically unsuitable, procurement teams can reconsider support requirements. Where downstream recovery records remain incomplete, asset managers can improve transfer procedures and clarify the evidence expected from receiving parties. These changes should respond to documented problems rather than assume one procedure will suit every equipment category. Over time, the audit can improve equipment planning and environmental reporting.
Management should also review whether corrective actions address the underlying causes of recurring problems. Better recordkeeping will not resolve a technical compatibility issue, and a new procurement clause will not guarantee that downstream reuse succeeds. The organization should assign responsibility for each improvement and establish how it will verify completion. Subsequent audits can then determine whether the change improved traceability or altered equipment decisions. Where the problem persists, teams should reconsider their approach. This makes lifecycle auditing a continuing improvement process rather than a one-time reporting exercise.
What a Credible Equipment Lifecycle Audit Should Establish
The purpose of an equipment lifecycle audit is not to replace electricity reporting with a longer list of environmental indicators. Its purpose is to establish whether the organization understands the consequences of its equipment decisions. That requires a consistent connection between procurement, manufacturing information, deployment, maintenance, upgrades, relocation, reuse, and final treatment. The audit should identify where records support firm conclusions and where estimates remain necessary. It should also explain how the organization evaluates competing options when extending equipment life or replacing hardware produces different consequences. A credible assessment makes those trade-offs visible instead of assuming that one operational improvement proves overall environmental progress.
Build the audit around decisions rather than isolated indicators
A useful lifecycle audit begins with decisions that materially affect equipment demand. When an organization considers a hardware refresh, the audit should examine the operational requirement, available alternatives, expected service life, and destination of displaced equipment. IF a cooling upgrade becomes necessary, it should assess which existing components remain usable. When equipment reaches retirement, the audit should establish whether repair, reuse, refurbishment, recovery, or recycling offers a suitable pathway. These assessments need not force every decision into a single environmental score. Instead, the audit should preserve the assumptions and supporting records needed to understand why the organization selected a particular option.
This decision-centered approach also helps distinguish environmental priorities from routine equipment administration. Not every repair or inventory adjustment requires a full lifecycle assessment. Significant decisions should receive enough scrutiny to explain their likely consequences. Teams should identify the relevant alternatives and establish the evidence available for each option. They should also record constraints that limit the comparison. The assessment must account for operational requirements rather than disregard reliability, security, or compatibility. When evidence remains incomplete, the organization should state the uncertainty and avoid presenting the preferred option as a proven environmental improvement.
The audit should also consider the practical consequences of the decision after implementation. A replacement may improve performance but leave usable equipment without a destination. A relocation may appear to extend service life but fail because the receiving environment cannot support the system. A recycling arrangement may provide a transfer record without confirming the final treatment outcome. These possibilities should remain part of the assessment. The organization should evaluate actual results rather than rely solely on the original plan. This helps distinguish an intended benefit from an outcome supported by evidence.
Make lifecycle evidence an ongoing operational responsibility
The most useful lifecycle audit remains connected to equipment management after the reporting period ends. Assets continue to change as workloads, configurations, maintenance requirements, and deployment priorities evolve. Organizations should update records when equipment moves, components change, refurbishment occurs, or a system leaves service. They should not rely on retrospective reconstruction when an audit begins. Teams should also review whether supplier documentation remains relevant to the products purchased. Where evidence cannot establish a claimed benefit, the reporting process should state that limitation clearly. This discipline creates a more defensible relationship between equipment decisions and environmental reporting.
Lifecycle evidence should support decisions across the equipment’s entire service period. Procurement records establish what entered the organization, deployment records show how the equipment was configured, and maintenance records explain significant changes. Transfer and retirement records then establish what happened when the original deployment ended. These records should remain connected so that the organization can follow an asset without reconstructing its history from unrelated documents. The appropriate level of detail will vary with the equipment and the significance of the decision. The objective is to make the lifecycle understandable and the resulting claims verifiable.
Data center sustainability audits become more meaningful when they follow equipment throughout its lifecycle. Electricity records show how infrastructure operates, while equipment records help explain the environmental consequences of acquiring, maintaining, upgrading, reusing, and retiring that infrastructure. Neither record alone answers every sustainability question. Together, they provide a stronger basis for evaluating operational performance and lifecycle impacts. The quality of the assessment depends on clear boundaries, reliable evidence, and honest treatment of uncertainty. A credible audit will not eliminate every information gap, but it can make those gaps visible and improve future equipment decisions.
The final objective is better infrastructure decision-making, not simply more extensive reporting. Operators need to understand whether replacement, repair, reuse, or retirement makes sense under their actual technical and operating conditions. They also need to know which environmental conclusions their evidence can support. A disciplined lifecycle audit connects those questions and identifies where better procurement records, maintenance practices, or transfer controls could improve the result. It complements electricity reporting rather than replacing it. By following the equipment alongside its energy use, organizations can build a more complete and defensible account of their infrastructure’s environmental performance.









