 Skip to content

The AI industry has spent the better part of a decade convincing itself that infrastructure is an execution problem, not a strategy problem. You raise the capital, hire the contractors, order the equipment, and build. The assumption embedded in that sequence was that the equipment would be available, that the supply chains feeding the build would remain open, and that the physical inputs to AI infrastructure were commodities to be procured rather than constraints to be managed. Tariffs have shattered that assumption. The reckoning is not coming. It is here, and the industry is only beginning to understand what it actually means for the pace and economics of the AI build-out it has been promising investors and customers for the past several years.

The Supply Chain the Industry Chose Not to See
Data center construction depends on a specific set of physical components that most of the AI industry’s leadership has never thought about in detail. Transformers, switchgear, busways, cooling systems, and the specialized electrical equipment that connects a facility to the grid never appear in funding announcements or hyperscaler earnings calls. They are the unglamorous infrastructure beneath the infrastructure, and Chinese manufacturers have produced the overwhelming majority of them for the better part of two decades.
That concentration was not accidental. Chinese manufacturers built cost and scale advantages in electrical equipment that Western producers could not match. The economics were compelling and the geopolitical risk seemed manageable. For most of that period it was. The AI infrastructure boom changed the calculation entirely, not because tariffs were inevitable, but because the volume of demand created a dependency so large that any disruption to the supply chain would produce consequences that could not be absorbed quietly. The dependency existed before the tariffs. The tariffs made it impossible to ignore. What the industry is now confronting is not a new problem that policy created. It is an old problem that policy finally forced into the open.
What Tariffs Actually Hit
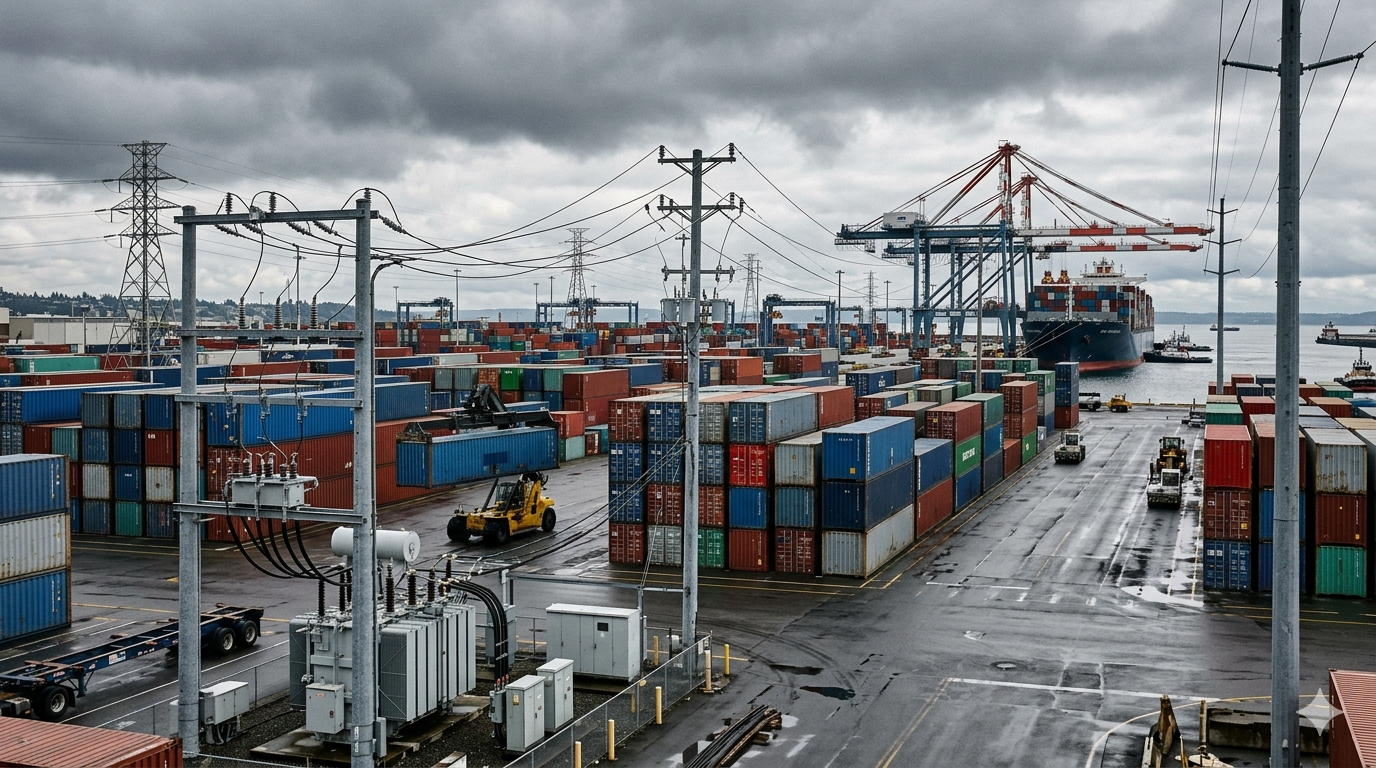
The specific components now facing significant tariff exposure are precisely the ones that data center developers need most urgently. Transformers sit at the center of the problem. A large AI campus requires multiple high-capacity transformers to step down grid voltage for facility use. As covered in our analysis of transformer and substation supply chains, lead times for these components were already stretching beyond two years before tariffs added cost pressure that makes domestic alternatives more attractive on paper but not yet competitive on availability.

The domestic transformer manufacturing base in the United States does not have the capacity to absorb the volume that the current AI infrastructure build-out demands, regardless of what tariff policy does to the price of imported alternatives. Building that capacity takes time that the market does not have. The developers who need transformers in 2026 and 2027 cannot wait for a domestic manufacturing base that might be meaningfully larger by 2029. They are managing a procurement crisis in the present tense, not a structural transition that policy will eventually resolve.
Switchgear, busways, and cooling system components face a similar dynamic. Projects that were already running into procurement delays before tariffs now carry an additional cost burden that changes project economics in ways that some developers had not modeled. A project that was marginally viable at pre-tariff component prices may not be viable at post-tariff prices if the developer cannot pass those costs through to customers whose capacity agreements were priced in a different environment. The contracts signed in 2024 and early 2025 did not anticipate the tariff environment that exists today. That mismatch is becoming a source of financial stress that the industry has not yet fully disclosed.
Why the Industry Ignored This for So Long
The honest answer is that ignoring the supply chain was rational for a long time. When the primary constraint on AI infrastructure was capital and hyperscaler commitment rather than physical components, the supply chain was not the binding constraint. Developers who spent management attention on transformer procurement and switchgear sourcing were optimizing a variable that did not determine outcomes. The capital and the customer relationships were what mattered. The equipment would follow.
That logic held until it did not. The transition point was not a single event. It was the accumulation of demand from dozens of large projects competing for the same pool of specialized components from a supply base that had not scaled to meet them. Tariffs arrived into a market already under supply pressure and added cost and uncertainty to a procurement environment that was already difficult. The industry did not create the supply chain vulnerability intentionally. It created it through a sustained, rational prioritization of the things that were actually scarce at the time. Those things have changed, and the organizational habits built around the old scarcity map have not changed with them.
There is also a cultural dimension to this that does not get discussed enough. The AI infrastructure industry grew up in a software-adjacent environment where supply chains are digital, marginal costs approach zero, and physical constraints are someone else’s problem. The people who raised the capital, struck the hyperscaler deals, and drove the build-out announcements came from backgrounds where procurement was a back-office function. The idea that a data center campus worth several billion dollars could be held up by a transformer that costs a fraction of that and takes two years to arrive was not part of the mental model. It is now.
What a Real Response Looks Like
Acknowledging the problem is not the same as solving it. The supply chain vulnerabilities that tariffs have exposed took decades to build and will take years to address meaningfully. Domestic manufacturing capacity for the electrical equipment that data centers require cannot be conjured quickly regardless of policy intent. The skilled workforce to operate that manufacturing capacity, the capital to build it, and the time to bring it online all represent constraints that tariff policy alone cannot resolve.
The developers and operators who navigate this period best will be those who treat supply chain access as a competitive asset rather than a procurement function. That means building relationships with manufacturers before demand peaks rather than after. It means making commitments that provide manufacturers with the demand visibility they need to justify capacity investment. It means accepting longer planning horizons and higher inventory carrying costs as the price of supply security in an environment where the alternative is project delays that cost more than the inventory ever would.
Some operators are already moving in this direction. The developers who secured transformer commitments and switchgear supply agreements in 2023 and 2024, before the current wave of demand compressed availability, are sitting on a procurement advantage that their competitors cannot replicate quickly. That advantage will show up in their ability to deliver capacity on schedule while others announce delays. It will show up in their project economics when component costs for competitors rise while their contracted prices hold. Supply chain foresight is becoming a form of competitive differentiation that was simply not visible when equipment was easy to obtain.
The Broader Lesson the Industry Needs to Learn
The AI industry is not uniquely culpable for the supply chain situation it now finds itself in. Every industry that scaled rapidly on the back of globally optimized supply chains faces some version of this reckoning when geopolitics disrupts the optimization. What makes the AI infrastructure case distinctive is the speed of the demand surge, the concentration of the supply base, and the fact that the physical components at risk are not optional features.
You cannot build a data center without transformers. Connecting it to the grid requires switchgear that comes from the same constrained supply base. Cooling it depends on components manufactured in the same geography that tariffs are now making more expensive and harder to source reliably. The supply chain is not a secondary concern. It never was. The industry just got away with treating it as one for longer than it should have, and the tariff environment has made that approach permanently untenable.
The companies that internalize this lesson now and restructure their procurement and planning functions accordingly will be better positioned for the next decade of AI infrastructure development than those who treat the current disruption as a temporary inconvenience to be managed until conditions normalize. Conditions are not going to normalize. This is the new normal, and the sooner the industry accepts that, the sooner it can build supply chains worthy of the ambitions it keeps announcing.










