Skip to content

AI Inference Is Starting to Meet a Power Constraint
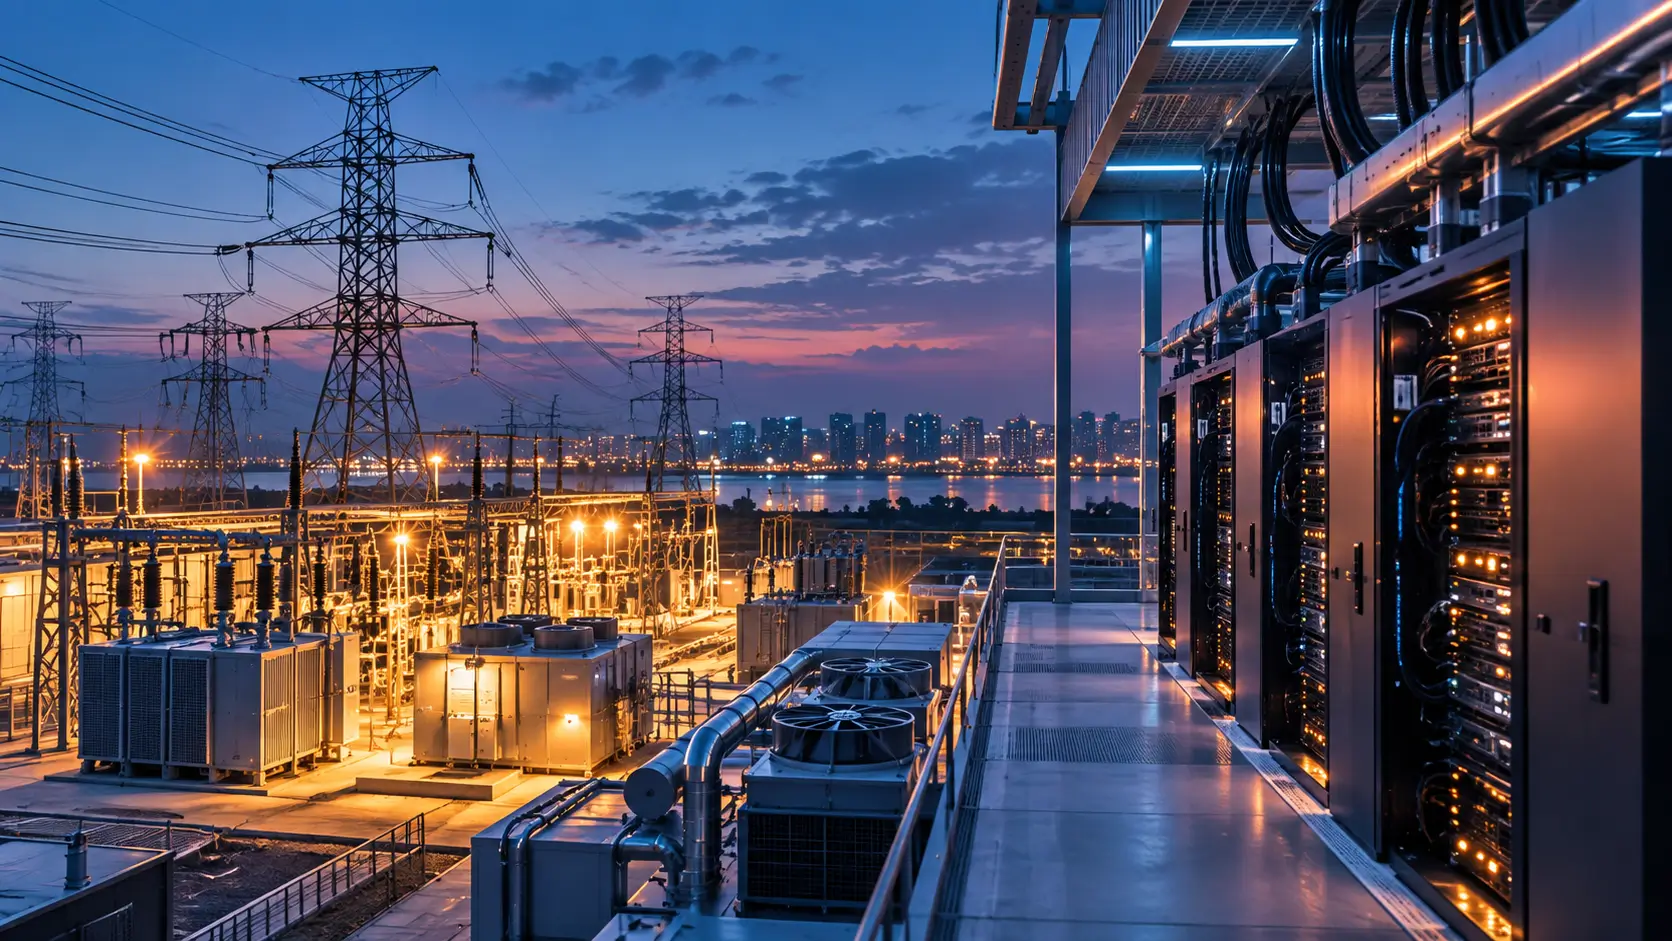
The next location decision for an AI workload may begin with an electrical question rather than a GPU question. Companies already spend considerable effort comparing accelerators, cloud platforms and inference architectures. They need performance that meets application requirements without pushing costs beyond acceptable levels. Yet the physical infrastructure supporting those choices is becoming harder to ignore. Electricity demand from data centres continues to grow. At the same time, grid connection queues and local infrastructure constraints can limit how quickly new computing capacity becomes operational. The International Energy Agency has warned that grid constraints could delay around 20% of global data-centre capacity planned through 2030. That does not mean existing inference workloads will suddenly leave congested regions. Congestion also does not affect every market equally.

For buyers, the issue is more specific. They may need to ask whether a location with attractive GPU capacity can support the electrical load required for expansion. That question could become increasingly important as inference demand grows. Geography could therefore become part of inference architecture rather than a detail hidden inside a provider’s infrastructure map.
Available Compute and Available Power Are Different Things
A provider can have access to accelerators without having unlimited ability to energise additional racks. That distinction matters because accelerated computing has increased the importance of power density. It has also placed greater demands on supporting infrastructure inside modern data centres. Compute availability and powered capacity cannot always be treated as the same thing. The International Energy Agency expects accelerated servers to drive a significant share of future electricity growth. Driven mainly by AI adoption, they could account for almost half of the net increase in global data-centre electricity consumption through 2030. Data centres also concentrate substantial electrical demand in particular locations. That demand does not spread evenly across a power system.
The resulting challenge is highly geographic. A region can attract strong demand for computing while facing constraints around transmission, substations, transformers or grid connections. An inference buyer focused only on accelerator pricing could therefore overlook conditions that influence future capacity expansion. Cheap advertised compute has limited value if additional capacity faces a slower power-delivery schedule. Buyers evaluating future inference requirements may therefore need a broader comparison. Computing economics still matter, but so does the infrastructure supporting future growth.

Inference Has a Flexibility Advantage When Workloads Can Move
Some inference workloads can support geographic flexibility when latency, capacity and regulatory requirements permit it. However, not every request can move freely. Data residency, network architecture, availability requirements and application design can all constrain placement. Those limitations make workload characteristics central to any geographic decision. Companies serving users across several regions may have additional placement options. Their choices increase when inference architecture allows requests to run across multiple compute locations. A flexible design could direct suitable workloads towards regions where computing and power capacity remain easier to expand.
That possibility changes the infrastructure conversation. Instead of finding one preferred AI region, companies can examine which workloads genuinely need to operate there. Latency-sensitive interactions might remain close to users. Less time-sensitive processing could have a wider geographic operating envelope. Batch inference, background processing and other delay-tolerant tasks may offer useful flexibility when application architecture permits it. That does not make every workload portable. Instead, it creates another variable that infrastructure teams can examine before assigning capacity. Grid congestion could therefore give workload classification a new financial purpose. Placement flexibility may help companies avoid concentrating every inference requirement behind the same constrained electrical connection. The value lies in knowing which workloads can move before additional capacity becomes difficult to secure.
Latency Could Become a Price Paid for Infrastructure Flexibility
Moving inference is not free. Electricity availability does not erase the physics of networking. Greater distance between an application, its data and its inference infrastructure can increase network latency. It can also introduce additional operational dependencies. Data movement can create costs that reduce the economic benefit of relocating computation. That consideration becomes particularly important for data-intensive applications. Regulatory requirements can further narrow the locations where particular datasets or workloads may operate. Geographic flexibility therefore comes with practical limits.
Companies should resist treating geographic distribution as a universal response to grid congestion. A better approach is to establish the latency, data, reliability and cost boundaries for each workload. Teams can do that before infrastructure becomes constrained. Once those boundaries become visible, infrastructure teams can separate movable inference traffic from workloads anchored to a region. That distinction could become valuable when a preferred market cannot add capacity quickly enough. In that situation, workload flexibility becomes an operational option rather than an emergency response.
Power Availability Could Become Part of AI Procurement
AI procurement has traditionally emphasised accelerator type, memory, performance and software compatibility. Networking and price also remain important considerations. However, infrastructure questions are moving closer to the buying decision as electricity demand rises. The scale of that demand is becoming difficult to ignore. The International Energy Agency reported in 2026 that global data-centre electricity demand rose 17% during 2025. Demand from AI-focused facilities grew even faster.
Berkeley Lab’s 2026 update provides another indication of the potential scale. It estimates that data centres could account for 9.5% to 15.3% of total US electricity consumption by 2030. The range also illustrates the uncertainty surrounding future demand. Those figures do not prove that any particular AI deployment will face a power shortage. They do show why customers should distinguish between existing compute and capacity that depends on future infrastructure expansion. The distinction becomes more important when customers expect workloads to grow quickly.
A multiyear inference agreement can carry additional delivery considerations. Customer demand may grow faster than the underlying site can add usable electrical capacity. Procurement teams may therefore need to understand how additional contracted compute maps to powered capacity. Accelerator supply alone does not determine every expansion timeline. Power infrastructure can also influence when additional capacity becomes usable. That creates a different conversation from simply comparing hourly GPU prices. For rapidly scaling applications, both questions may become increasingly important.
The New AI Map May Follow Deliverable Megawatts
The infrastructure map for inference may not simply follow regions with the largest existing accelerator clusters. Power availability could increasingly influence where additional capacity becomes practical. Operators need grid connections and supporting electrical infrastructure to accommodate customer growth. The International Energy Agency notes that transmission development in advanced economies can take four to eight years. That timeline highlights a potential mismatch between digital infrastructure expansion and major grid construction. Compute demand can develop on a different schedule from the infrastructure needed to support it.
That gap gives AI buyers a reason to examine the expansion path behind purchased capacity. Future scale should not automatically be treated as an extension of current availability. Buyers may need to understand what physical infrastructure supports the next stage of growth. Some applications will remain tied to particular regions. Latency or data requirements can make relocation impractical. Other workloads could become geographically portable enough for infrastructure availability to influence placement.
Understanding that distinction gives companies more information before congestion becomes an application constraint. It also changes what an AI capacity decision can involve. GPU availability remains important, but it may represent only one part of the deployment equation. In that environment, the most important location for the next inference workload may not be where GPUs are easiest to find. It could be where computing, networking and deliverable power can arrive on compatible schedules. For AI buyers, that makes grid capacity part of the infrastructure conversation rather than somebody else’s problem.